Choosing a mortgage broker based on their fee alone might seem like a sensible way to save money. However, a real client scenario shows why the overall cost of your mortgage deserves just as much attention.
An existing client recently returned to us to check a mortgage rate they had been offered through another broker. When we looked at the figures, the rate itself was the best available at that point. However, the client explained that they had started working with the other broker around three to four weeks earlier.
During that time, the available mortgage rate had increased by 0.5%.
That change worked out at approximately £937 extra per year, or around £4,685 over a five-year deal.
The client had originally chosen the other broker because their fee was slightly cheaper. This experience highlights an important consideration when choosing a mortgage broker: saving money on the initial fee does not necessarily mean getting the cheapest overall mortgage outcome.
How Much Can a Mortgage Rate Change Cost?
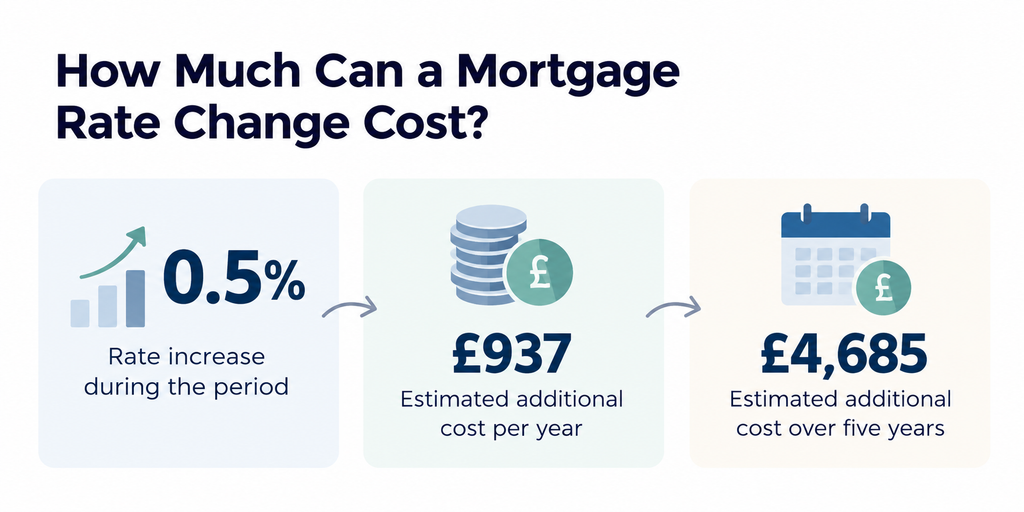
These figures relate to one client’s circumstances at a particular point in time. The financial impact of a rate change will vary depending on the mortgage amount, the rate available and the direction in which rates move.
A Real Client Scenario: When a Cheaper Broker Came at a Higher Cost
The situation began when an existing client decided to use another mortgage broker because their fee was slightly cheaper. The client started the process around three to four weeks before eventually coming back to us. During that period, it took the other broker that long to come back with mortgage options.
When the client returned, they asked us to check the mortgage rate they had been offered. We reviewed it and confirmed that, at that point, it was the best rate available. Out of curiosity, we asked why they had not come back to us originally and how long they had been dealing with the other broker. That was when the timeline became clear.
The client had been waiting around three to four weeks for their mortgage options, and the available rate had increased by 0.5% during that period.
The result was a potential additional mortgage cost of approximately £4,685 over five years.
This is not about suggesting that a cheaper broker will always provide a worse outcome. It is about recognising that the fee is only one part of the decision. How quickly you receive your options, how well you are kept informed and how accessible your broker is can all matter when mortgage rates are changing.
How a 0.5% Mortgage Rate Increase Could Cost £4,685
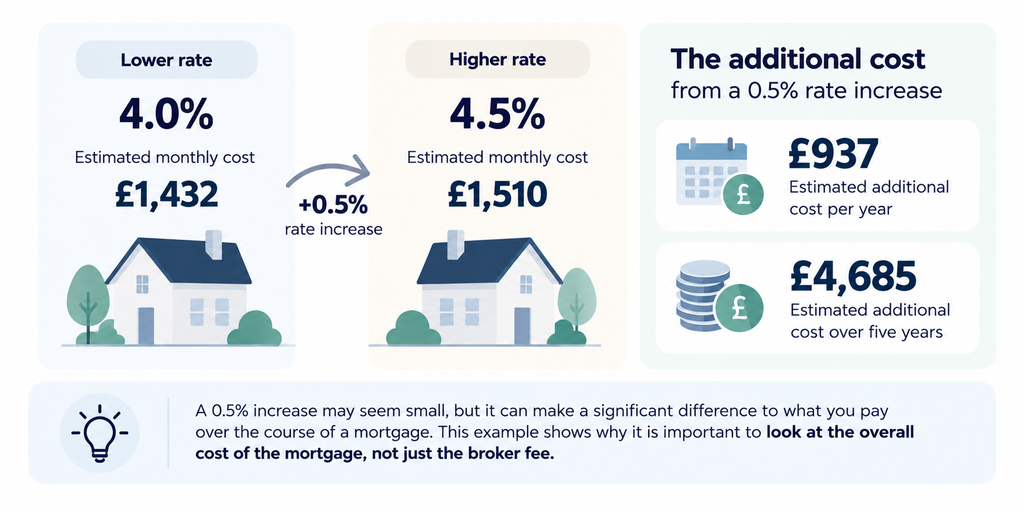
A change of 0.5 percentage points might not sound particularly significant at first. However, depending on the amount you borrow, even a relatively small change in the mortgage rate can make a meaningful difference to the cost of borrowing.
In this client’s case, the 0.5% increase worked out at approximately £937 extra per year. Over a five-year deal, that amounted to around £4,685. Compare that potential additional cost with saving £100–£200 on a broker fee, and the difference becomes easier to understand.
The original fee saving may have seemed worthwhile, but the potential additional mortgage cost was considerably higher. It is important to remember that this is an illustration based on one client’s circumstances, not a calculation that applies to every mortgage. The actual impact of a rate change depends on factors including the amount borrowed and the mortgage terms.
The wider lesson is straightforward: when comparing mortgage brokers, look at the potential overall cost of the mortgage, not just the fee you pay for the advice.
Broker Insight: Look Beyond the Fee
When choosing a mortgage broker, it is natural to compare fees, especially when you are trying to keep the costs of buying a home or remortgaging under control. However, the fee is only one part of the overall picture. It is also worth considering how quickly you can expect to receive your mortgage options, how clearly your broker communicates with you and how easily you can get in touch when you need an update.
As this client’s experience illustrates, saving £100–£200 on a broker fee may seem worthwhile at first, but the potential additional mortgage cost can be considerably higher if rates move during a delay. Of course, no broker can control the mortgage market or guarantee that a particular rate will remain available. What matters is having a broker who keeps you informed, responds promptly and helps you understand the options available so you can make an informed decision.
Why the Cheapest Mortgage Broker Doesn’t Always Mean the Cheapest Outcome
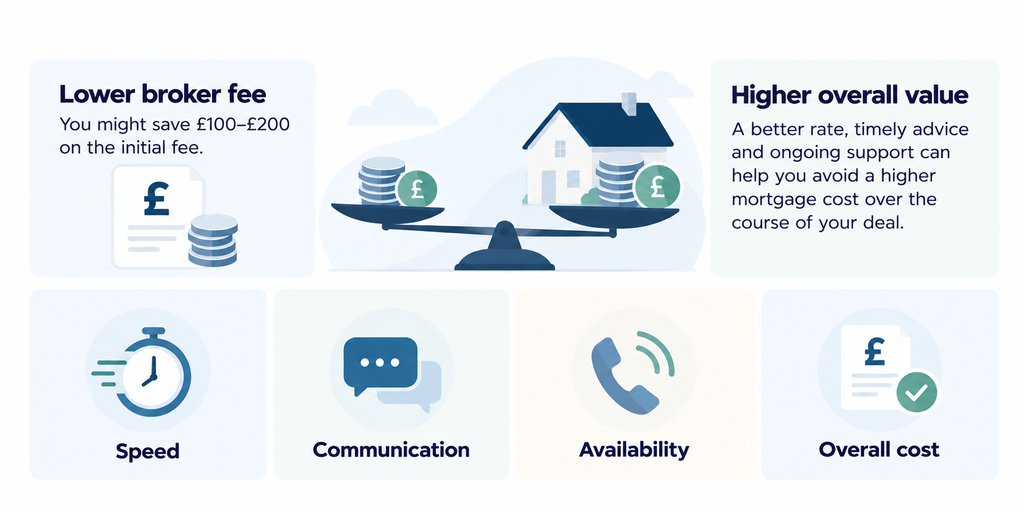
Mortgage broker fees are a legitimate consideration. You should understand what you are paying, what the fee covers and how it fits into your overall costs.
However, the lowest fee does not automatically represent the best value.
A mortgage is a significant financial commitment, and the interest rate can have a substantial effect on what you pay over the course of a deal. Saving £100–£200 on a broker fee may be less important than understanding your options promptly and being able to make an informed decision when a suitable mortgage product is available.
There are several aspects of the service worth considering alongside the fee:
- Speed: How quickly will the broker assess your circumstances and present suitable mortgage options?
- Communication: Will you be kept informed about progress and any developments that could affect your choices?
- Availability: Can you contact your broker when you have questions or need an update?
- Overall cost: Will the advice help you understand the wider costs of the mortgage, including the rate, fees and relevant terms?
A higher broker fee does not automatically mean better service, just as a lower fee does not automatically mean worse service. The important thing is to compare what you are getting and consider the overall value.
Why Speed Matters, Even When You Don’t Know Which Way Rates Will Move
Mortgage rates do not always move in the direction borrowers hope. They can rise or fall as market conditions and lenders’ pricing change.
In this client’s situation, the available rate had increased by 0.5% during the period they were waiting for their options. That meant the delay coincided with a less favourable rate environment for the client.
If rates had moved in the opposite direction, the outcome could have been different. The underlying point, however, would remain the same: while you are waiting for mortgage options, the rates available to you may change.
What happens before a mortgage rate is secured?
Receiving mortgage options and securing a mortgage rate are not necessarily the same thing. The process depends on the lender, the product and the stage your application has reached.
A broker may be able to help you review suitable options and understand the next steps promptly, but a rate is not automatically reserved simply because options have been discussed. Whether a rate can be secured, and when, depends on the lender’s process and requirements. Acting promptly can give you the opportunity to consider the available options before they change. It cannot guarantee that rates will remain available, that they will not increase or that a particular rate will be the cheapest one.
This is why speed should be considered alongside communication and availability. When rates are moving, knowing where you stand and being able to discuss your options can make a real difference to your decision-making.
In the client’s case, the three-to-four-week wait is an important part of the story. It illustrates why the service and timing involved in arranging a mortgage deserve consideration alongside the broker fee.
What Should You Consider When Choosing a Mortgage Broker?
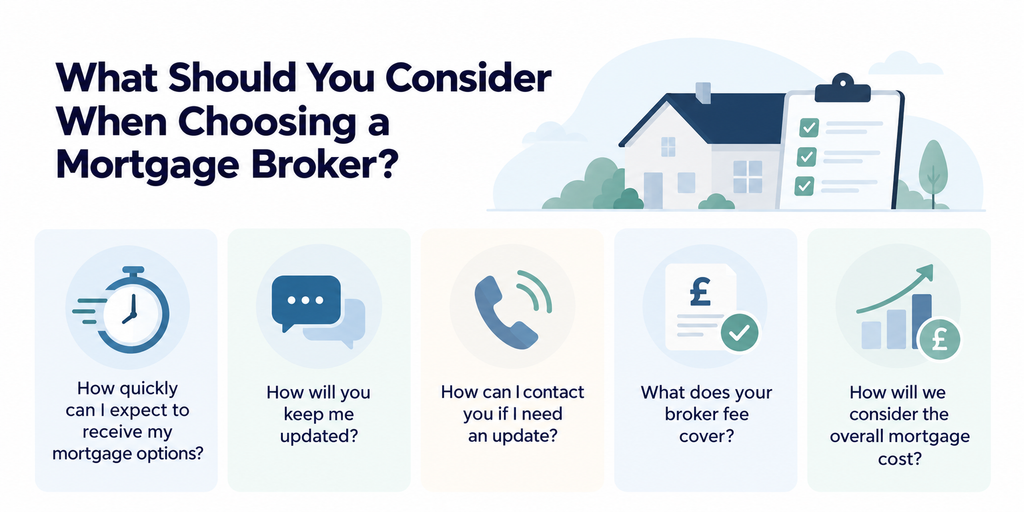
If you are comparing mortgage brokers, the fee is a useful starting point, but it should not be your only consideration.
Using a mortgage broker is already a common choice for UK homebuyers. The Financial Conduct Authority (FCA) reported that around 90% of first-time buyers and 78% of home movers purchased through a broker in 2023. With so many buyers using mortgage advice, it is worth looking beyond the initial fee and considering the service, communication and support you will receive.
Here are some practical questions to ask before deciding who to work with.
How quickly can I expect to receive my mortgage options?
Ask about the broker’s process and the information they need from you to assess your circumstances. Timescales will depend on the complexity of your case and the information available, so avoid assuming that every application can be handled at the same speed.
How will you keep me updated?
Clear communication helps you understand what is happening and whether anything is needed from you. Ask how progress will be communicated and how you can raise questions.
How can I contact you if I need an update?
Accessibility matters throughout the process. Understand how to reach your broker and what communication arrangements you can expect.
What does your broker fee cover?
Make sure you understand the fee, when it is payable and what service it covers. This allows you to compare brokers on a clearer basis.
How will we consider the overall mortgage cost?
The interest rate is important, but it is not the only factor. Mortgage fees, product terms and other relevant costs can affect which option is appropriate for your circumstances.
Ultimately, you want to understand both the service you will receive and the mortgage options available to you. Comparing those factors gives you a more complete picture than looking at the fee alone.
How Everest Mortgages Can Help
At Everest Mortgages, we understand that arranging a mortgage involves more than finding a rate. It is also about understanding your circumstances, reviewing the available options and helping you make informed decisions.
We aim to provide clear communication, remain accessible throughout the process and help clients understand their options when mortgage rates are changing. Every case is different, and mortgage rates and lender criteria can change. No broker can guarantee the lowest rate or prevent the market from moving. However, having a clear understanding of your options and the next steps can help you make decisions with greater confidence.
Whether you are buying your first home or reviewing an existing mortgage, we can help you explore the options available for your circumstances. You can also use our mortgage calculator to get an initial estimate of your potential monthly repayments and help you understand how mortgage costs could fit into your budget.
Thinking about your next mortgage? Speak to Everest Mortgages to discuss your circumstances and understand the options available to you.
Frequently Asked Questions
Choosing a mortgage broker and understanding how rate changes could affect your mortgage can raise a few important questions. Here are some common questions about broker fees, mortgage rates and why timing matters when arranging a mortgage.
Can choosing a cheaper mortgage broker cost you more?
It can, depending on the circumstances. A lower broker fee does not guarantee the lowest overall mortgage cost. If rates change while you are waiting for options, the mortgage available to you may become more expensive. However, the outcome depends on the individual case, and a cheaper broker does not automatically mean a worse result.
Why does timing matter when choosing a mortgage broker?
Mortgage rates can change while you are arranging a mortgage. A broker who communicates clearly, responds promptly and helps you understand the next steps can make it easier to consider the options available at that time. Speed does not guarantee a better rate, but delays can mean that the options available to you change.
Can mortgage rates change while I’m arranging a mortgage?
Yes. Lenders can change the rates and products they offer. The rate available when you first enquire may not be the same as the rate available later. Whether a particular rate can be reserved depends on the lender’s product terms and application process.
Should I choose a mortgage broker based on their fee?
The fee should be part of your decision, but it is worth considering the wider service too. Look at communication, accessibility, expected timescales and how the broker helps you understand the overall cost of your mortgage. The aim is to compare value rather than price alone.
What does it mean when a broker locks in or reserves a mortgage rate?
It generally refers to securing a particular mortgage product or rate under the lender’s process and conditions. The exact process, timing and any conditions depend on the lender and product. Discuss with your broker when a rate can be secured and what could affect its availability.
Disclaimer
This example is based on one client’s real circumstances and is provided for illustrative purposes only. Mortgage rate movements, timescales and their financial impact will vary for every individual and cannot be guaranteed.
Everest Mortgage Services is authorised and regulated by the Financial Conduct Authority (FCA). The Financial Services Register number is 786425.
Your home may be repossessed if you do not keep up repayments on your mortgage.