
Mortgages for teachers
Find your perfect mortgage
Whole-of-market advice from a qualified broker – we search every lender to find your best deal.
Qualified Mortgage Adviser & Founder
As featured in


FCA
regulated
Fully authorised & regulated
by the FCA
100%
independent
Whole-of-market access.
No lender ties
1000+
mortgages arranged
for happy clients
Facts at a Glance
Everest Mortgages | Mortgage Broker for Teachers, Brighton & Sussex
Specialist experience with teachers and education professionals · Some specialist lenders may offer up to 7x income, subject to criteria · Whole-of-market · FCA regulated · CeMAP qualified · Independent, no lender ties
Mortgages for Teachers
Specialist mortgage advice for teachers and education professionals in Brighton, East Sussex and West Sussex
If you work in education, your mortgage options may be different from those available to a standard employed applicant.
At Everest Mortgages, we have arranged lots of mortgages for teachers and education professionals and understand that teaching careers do not always follow a straightforward employment pattern. Whether you are an experienced teacher, an Early Career Teacher, a supply teacher, working on a fixed-term contract or employed elsewhere within education, we can help you understand your options.
As an independent, whole-of-market mortgage broker, we can look at your circumstances and consider a wide range of lenders rather than being tied to one provider.
If you are looking to buy a home or remortgage in Brighton, East Sussex, West Sussex or elsewhere in the UK, we can help you understand what may be available.
Can Teachers Get a Mortgage?
Yes, teachers can get mortgages.
However, the mortgage you may be able to obtain depends on your individual circumstances and the criteria used by the lender.
For teachers, this can include things such as your salary, pay scale, employment status, allowances, contract type, deposit, existing commitments and overall affordability. Some lenders also have specialist criteria for people working in education. This can be particularly relevant if you are newly qualified, working on a fixed-term contract or working as a supply teacher.
This is where speaking to an experienced mortgage broker or mortgage adviser can be useful. Rather than assuming that the mortgage offered by your bank is the only option, you can look at the wider range of lending criteria available.
At Everest Mortgages, we work with teachers and education professionals regularly and can help you understand what your circumstances could mean for your mortgage application.
Takes under 3 minutes
Get your mortgage in principle
today
today
Find out how much you could borrow in minutes. No credit check, no commitment — just clear, honest mortgage advice.
Get my mortgage in principle
→
Free review · No credit checks · No obligation
Why Teachers May Need Specialist Mortgage Advice
Teachers can apply for a mortgage just like other homebuyers. You do not necessarily need a specialist mortgage simply because you are a teacher.
The important point is that different lenders have different criteria for assessing teacher income and employment circumstances. One lender may offer a mortgage based on its standard affordability criteria, while another may be more comfortable with the way teachers are paid and may be able to offer a higher level of borrowing.
This can be particularly important if you are:
- Working on a standard permanent teaching contract
- An Early Career Teacher (ECT), formerly known as an NQT
- Working on a fixed-term contract
- Working as a supply teacher
- Receiving additional allowances
- Moving between schools
- Starting a new teaching position
- Working in another education profession
The way these circumstances are treated can vary between lenders. For example, one lender may have specific criteria for a teacher on a fixed-term contract, while another may take supply income, allowances or future pay progression into account.
Different Lenders Can Offer Different Borrowing
This is where specialist mortgage criteria can make a difference.
A teacher may be able to get a mortgage from a mainstream lender based on standard affordability criteria. However, some specialist lenders have criteria designed around particular professions and may be able to offer higher income multiples to eligible teachers and education professionals.
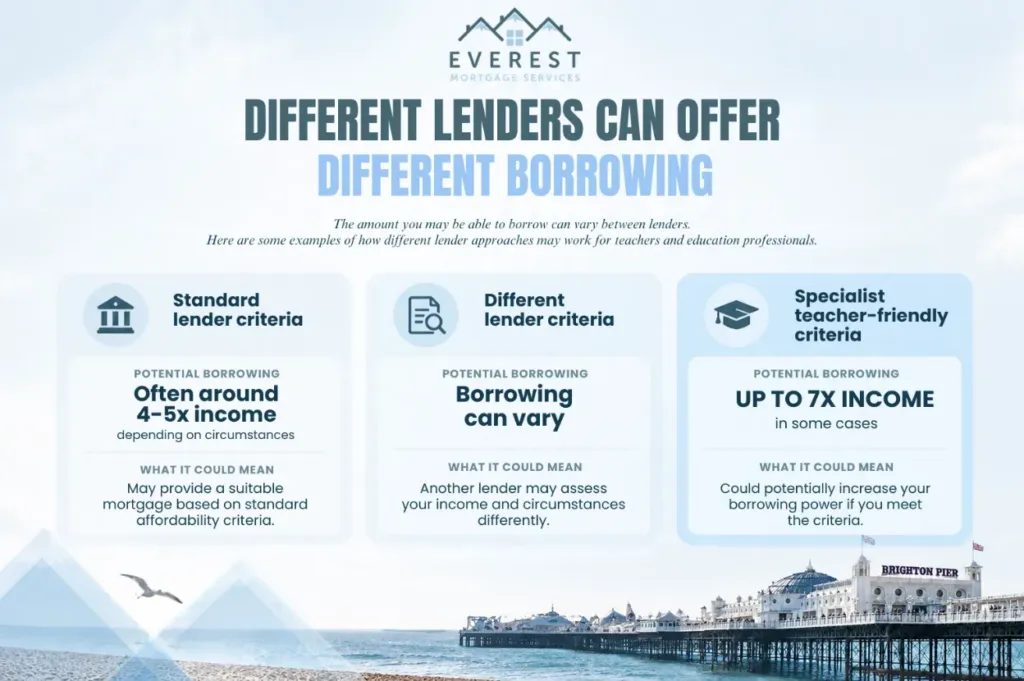
These figures are examples rather than guarantees. The amount you can actually borrow depends on your individual circumstances and the lender’s criteria.
As an independent, whole-of-market mortgage broker, Everest can search across a wide range of lenders to understand which criteria may be suitable for your circumstances.
We search 1000's of mortgage deals across a large number of lenders, including...


How Much Can a Teacher Borrow? Up to 7 Times Income
One of the key things to understand when looking at a mortgage is that lenders can use different income multiples when assessing how much you may be able to borrow.
For example, if a lender uses a 4.5 times income multiple and you earn £40,000 a year, that could give an initial borrowing figure of £180,000 before the lender considers your wider circumstances.
For eligible teachers and education professionals, some specialist lenders can offer up to 7 times income, subject to their lending criteria and a full affordability assessment.
For example:
£40,000 income × 7 = £280,000
This is simply an illustration of how a 7 times income multiple works. It does not mean that someone earning £40,000 will automatically be offered a £280,000 mortgage.
The lender will still consider your individual circumstances, including your income, regular expenditure, existing financial commitments, deposit, credit history and the property you are looking to buy.
A higher income multiple can make a significant difference, particularly for teachers looking to buy in areas where property prices are high compared with salaries. It is also important to remember that being able to borrow more does not necessarily mean you should borrow the maximum available. Your mortgage needs to be affordable alongside your other household costs and financial commitments.
The important thing is to understand what you could potentially borrow and which lenders may be able to offer it, rather than assuming that the borrowing figure from your own bank is necessarily the maximum available to you.
Read our reviews
Is 7 Times Income Available from Every Lender?
No.
The 7 times income figure is only available through certain specialist lenders’ criteria, and even then you would still need to meet their eligibility requirements and pass a full affordability assessment.
This is why it can be useful to look beyond your own bank. Different lenders may assess income, employment circumstances and affordability differently.
As an independent, whole-of-market mortgage broker, Everest can compare a wide range of lenders to see which criteria may suit your circumstances.
Trusted mortgage advice
Why choose Everest Mortgages?
Independent, whole-of-market advice from advisers who put you first — every time.
🛡️
Advisers you can trust
We're totally impartial and focused on finding the perfect mortgage to suit you — not the lender.
🔍
We search the market for the best deals
We work with all lenders, big and small, to give you exclusive access to a comprehensive range of mortgage rates.
🗓️
We work to your schedule
We're flexible to fit around you — evenings, weekends, whatever works best for your life.
✨
We take away the hassle
We deal with lenders on your behalf, so everything from paperwork to negotiation is completely stress-free.
🤝
We're supportive and friendly
Our highly experienced advisers make the entire buying process painless by taking all the work off your hands.
John Everest
Qualified Mortgage Adviser & Founder
Book a free consultation with a mortgage expert
John is a CeMAP-qualified, whole-of-market mortgage adviser and Director of Everest Mortgage Services. With over 21 years in financial services, and a track record of 1,000+ mortgages arranged.
- 15-minute call, no commitment
- Whole-of-market, FCA regulated
- Clarity and confidence in your next move
14+
Years experience
1,000+
Mortgages arranged
Mortgage tools
Find out how much you can borrow
Use our free calculator to get an instant estimate based on your income — no credit check, no commitment.
💰
How much can I borrow?
Applicant 1
Applicant 2
💰
Your results
Director note: Limited company directors can use dividends or shares on net profits to obtain their affordability.
Enter your details for an accurate range.
Estimated borrowing
Low (4.5x)
£0
Medium (5x)
£0
High (6x)
£0
Need the maximum loan possible?
Specialist lenders may go higher.
Free consultation
Ready to find your perfect mortgage?
Get in touch today and one of our qualified advisors will be in touch to guide you through your options.
✓
Free, no-obligation advice
No cost to speak with a qualified adviser.
🔒
No credit checks
Your credit score won't be affected.
⚡
Fast response
We aim to get back to you within 2 hours.
🏛️
FCA regulated
Fully authorised and regulated by the FCA.
Everest’s Experience with Teachers and Education Professionals
At Everest Mortgages, we have arranged lots of mortgages for teachers and education professionals.
We understand that there is no single type of teacher mortgage application. An experienced teacher with a permanent contract may have very different circumstances from an Early Career Teacher, supply teacher, lecturer, teaching assistant or other education professional.
As an independent, whole-of-market mortgage broker, we can look at the relevant lender criteria for your circumstances and support you through the practical side of the mortgage process, including the paperwork and application itself.
John’s View on Teacher Mortgages
According to John Everest, teacher mortgage applications are not necessarily different from other mortgage applications. The difference is that some lenders specifically favour teachers and understand their pay structure, which can affect how much they are prepared to lend.
One thing John wishes more teachers knew is that their own bank is not necessarily their only option. Other lenders may be able to lend more, depending on the teacher’s circumstances and the lender’s criteria.
“Let’s be honest, teachers are underpaid for their job role, and this is where knowing what lender to go to can make a huge difference to the borrowing and purchasing power.”
John also points out that lenders do not all assess applications in the same way. They can offer different borrowing amounts and have different policies and criteria, so there is no one-size-fits-all approach.
For teachers buying with a partner, there is another important point to understand: only one applicant needs to be a teacher for some specialist teacher mortgage options to apply. The same principle can apply to other education professionals, not just people whose job title is “teacher”, depending on the lender’s criteria.
For some teachers, getting onto the property ladder can be challenging, particularly where house prices, deposits and mortgage affordability do not comfortably align with their income. Research by teachers’ union NASUWT found that 72% of surveyed teachers aged 30 and under believed there was insufficient affordable housing for teachers in their area, while 32% said increases in mortgage or rent payments were affecting their finances.
This highlights why understanding your mortgage options can be particularly important if you work in education. The amount you can borrow is not simply about your job title or basic salary. Different lenders can assess income, employment circumstances and affordability in different ways.
The following is a real Everest Mortgages case study and shows how we approached an individual teacher’s circumstances.
Teacher Mortgage Case Study
The Situation
A first-time buyer couple wanted to purchase their first home together. They had a 10% deposit ready and were keen to move into their own home.
One applicant was a teacher and the other had CCJs and defaults on their credit history. This made it difficult for the couple to borrow enough through high-street lenders.
They could potentially borrow together, but the rate available was around 7.73%, which made the mortgage much less attractive.
The Challenge
The couple needed to find a way to achieve the level of borrowing they needed without relying on a mortgage that came with a significantly higher interest rate.
The challenge was to look beyond the standard high-street options and consider whether the teacher’s income could support the required borrowing on its own.
How We Helped
We looked at the property the couple wanted to purchase and considered what they needed to borrow within their budget.
We then assessed the application using just the applicant with the good credit history, who was a teacher, and looked across our lender options for criteria that could work for those circumstances.
The Outcome
We were able to secure the level of borrowing the couple needed based on the teacher’s income alone with a specialist lender whose criteria suited the application.
This meant they could move forward with their plans to buy their first home together.
What This Shows
This case highlights why it can be important to look beyond a single lender when applying for a mortgage. The couple’s circumstances meant that a standard high-street approach did not give them the borrowing or rate they needed, while another lender’s criteria provided a route forward.
The right lender will depend on the individual circumstances of each application.
Mortgages for Different Types of Education Professionals
Teacher mortgages are not limited to people working in permanent classroom roles.
Different education professionals can have different employment arrangements, and some lenders have specialist criteria that may be able to accommodate these circumstances. This means you may still have mortgage options even if your employment does not fit the standard permanent employee profile.
Early Career Teachers and Newly Qualified Teachers
If you have recently qualified as a teacher, you may be wondering whether you need to wait until you have several years of employment history before applying for a mortgage.
That is not necessarily the case. Some specialist lenders have criteria that can take an Early Career Teacher’s new role or confirmed employment into account. The exact approach varies between lenders, so it is important to check the criteria that apply to your circumstances.
Supply Teachers
Supply teaching does not necessarily prevent you from getting a mortgage.
Your income and employment history will need to be assessed, but some specialist lenders have criteria specifically designed to consider supply teachers. This can be particularly useful if your income does not look like a standard permanent employee’s payslip.
Can supply teachers get a mortgage?
Yes. Supply teachers can get mortgages, even when their work is arranged through an agency or involves assignments at different schools.
The main consideration is how the lender assesses your income and employment history. Rather than relying on a permanent contract, some lenders may consider your regular supply earnings and evidence of continued work.
You may be asked to provide:
- Recent payslips from your agency or employer.
- Bank statements showing regular income payments.
- Details of your current supply arrangements.
- Previous assignment history or evidence of ongoing work.
- Confirmation of your employment status and payment structure.
If your income changes between school terms or assignments, lenders may look at a longer period to establish an average. Some may also want evidence that your work is likely to continue.
Does it matter if you are a supply teacher employed through an agency?
It can. Supply teachers may work through an agency as PAYE employees or operate on a self-employed basis. The distinction matters because lenders can assess these income arrangements differently.
If you are paid through PAYE, lenders may assess your payslips, employment history and regular agency income. If you work on a self-employed basis, they may request tax calculations, tax year overviews or business accounts, depending on your circumstances.
It is important to establish how you are paid before choosing a lender, as the evidence required and affordability calculations may differ.
Contract and Fixed-Term Teachers
Teachers working on fixed-term or contract arrangements can also have mortgage options.
Lenders may look at factors such as your employment history, the length of your current contract and your experience in the profession. The criteria can differ significantly between lenders, which is why specialist advice can be useful.
Can teachers on fixed-term contracts get a mortgage?
Yes. Working on a fixed-term teaching contract does not automatically prevent you from getting a mortgage. Lenders may consider your current contract, employment history and the likelihood of continued work when assessing your application.
They may look at:
- Time remaining on your contract: How long you have left in your current teaching position.
- Previous employment history: Whether you have worked consistently in education or renewed similar contracts.
- Future employment prospects: Whether you have another contract lined up or a reasonable expectation of continued work.
- Income and affordability: Whether your salary and other regular income can support the proposed repayments.
Some lenders may accept applicants with a relatively short contract, while others may require a longer employment history or evidence of renewal. Criteria vary, so it is worth checking which lenders are suitable before applying.
Teaching Assistants
Teaching assistants are also part of the wider education profession and may be eligible for mortgage lending depending on their income and circumstances.
Your borrowing capacity will depend on the lender’s affordability assessment rather than simply your job title.
Lecturers and Headteachers
Education professionals such as lecturers and headteachers can also have their own income structures and employment arrangements.
Whether you are at the beginning of your career or in a senior education role, the same principle applies: the mortgage needs to be assessed against your individual circumstances and the relevant lender criteria.
Nursery Workers and Other Education Professionals
The education sector covers a broad range of roles.
If you work in education but are unsure whether specialist mortgage criteria could apply to you, it is worth asking rather than assuming you will be treated in exactly the same way as a standard employed applicant.
Teacher Mortgages for First-Time Buyers
Buying your first home can be exciting, but working out how much you can borrow and which mortgage options may be available can also feel complicated.
If you are a teacher buying your first home, we can help you understand:
- How much you may be able to borrow
- How your income and allowances could be assessed
- What deposit you may need
- Which lender criteria could apply to your circumstances
- What your monthly repayments and next steps could look like
You do not need to understand the entire mortgage process before speaking to us.
Getting advice early can help you establish a realistic budget before you start viewing properties or making offers. It can also help you understand whether your own bank’s borrowing figure is the only option available to you, or whether other lenders may assess your circumstances differently.
This can be particularly important in areas such as Brighton and Hove, East Sussex and West Sussex, where property prices can vary considerably between locations.
For more information about the wider first-time buyer process, check our First-Time Buyer Mortgage Guide.
Mortgages for Teachers in Brighton, East Sussex and West Sussex
If you are a teacher buying a home in Brighton and Hove, Lewes, Eastbourne, Hailsham, Seaford, Worthing, Shoreham-by-Sea, Chichester, Horsham or elsewhere across Sussex, understanding which lenders may be able to work with your circumstances can be particularly important.
Property prices and affordability can vary considerably across the region, so the amount you can borrow may have a significant impact on the properties available to you.
Everest Mortgages is based in Brighton and works with teachers and education professionals across the region. As an independent, whole-of-market mortgage broker, we can look across a wide range of lenders rather than limiting you to the options available from your own bank, including specialist criteria that may allow higher borrowing for eligible applicants.
Whether you are a first-time buyer, moving home or remortgaging, we can help you understand what mortgage options may be available based on your individual circumstances. See all areas covered by Everest Mortgages.
Partner offer
See your credit file from all 3 agencies
Everest Mortgage Services has an affiliate relationship with Checkmyfile. Try it free for 7 days and spot any issues before a lender does.
Experian
Equifax
TransUnion
Start my 7-day free trial
→
7 days free, then £14.99 a month · Cancel anytime
What Documents Might Teachers Need for a Mortgage?
When applying for a mortgage, you will usually need to provide documents that confirm your identity, income, employment and financial circumstances.
For teachers, the exact documents required can vary depending on your employment arrangement and the lender’s criteria. You may be asked for:
- Proof of ID: Passport or driving licence
- Proof of address: Utility bill or bank statement, usually from the last three months
- Proof of income: Recent payslips and, where relevant, evidence of additional income or allowances
- Bank statements: Typically covering the most recent three months
- Proof of deposit: Savings statements or a gifted deposit letter if the deposit is being provided by family
- Credit and financial commitments: Details of loans, credit cards and existing finance
- Employment information: Details of your employer, role and employment status
- Contract information: Where relevant, particularly if you are on a fixed-term contract or working as a supply teacher
Some lenders may assess certain types of teacher income differently, so having the right information available can help when comparing your options.
You do not need to know exactly which documents every lender will require before speaking to us. We can explain what is likely to be needed based on your circumstances and the lender being considered.
How the Teacher Mortgage Process Works
Getting a mortgage as a teacher follows the same basic process as any other mortgage application. The important difference is that your employment, income and circumstances may be assessed differently depending on the lender.
At Everest Mortgages, we start by understanding your situation before looking at which mortgage options may be suitable.
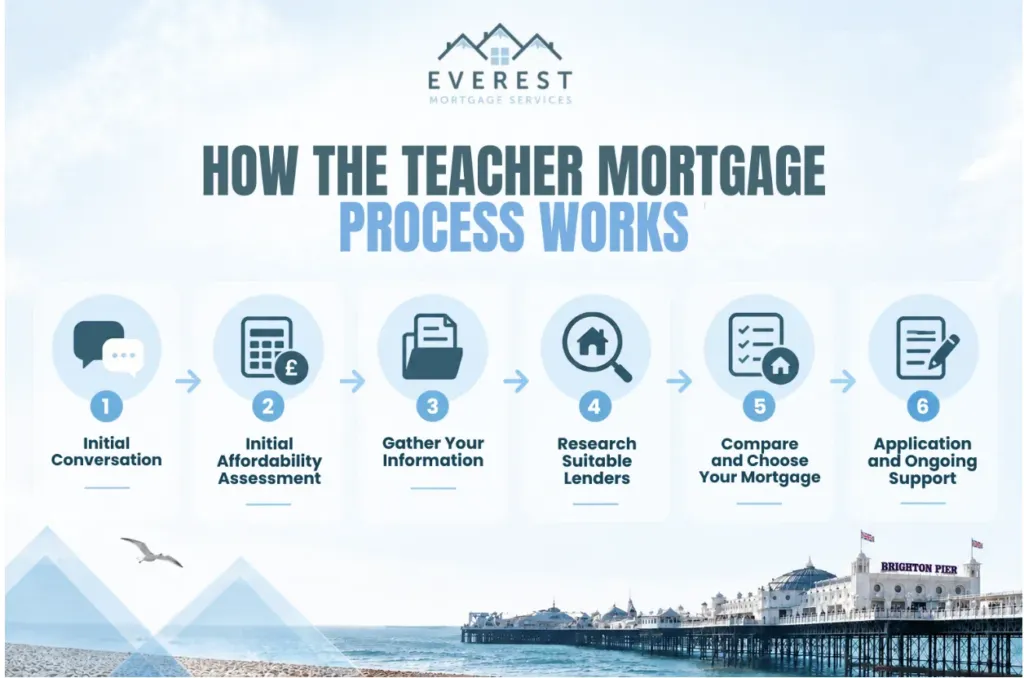
1. Initial Conversation
We discuss what you are looking to do, how much you may want to borrow, your deposit or equity, your income and employment, and anything you already know about your credit history.
For teachers, this can also include whether you are permanently employed, an Early Career Teacher, working on a fixed-term contract, a supply teacher or employed elsewhere within education.
2. Initial Affordability Assessment
We look at your income, expenditure, deposit and existing financial commitments to get an initial indication of what you may be able to borrow.
More complex circumstances may require additional information or documents before a more accurate assessment can be made.
3. Gather Your Information
If you decide to move forward, we set you up on our secure client portal, where you complete your fact-find and upload the documents needed to assess your circumstances properly.
4. Research Suitable Lenders
We review your circumstances and research lenders and mortgage options that may fit your situation.
As an independent, whole-of-market mortgage broker, we can look across the market rather than being tied to one lender.
5. Compare and Choose Your Mortgage
We talk you through the relevant options, including the costs, terms and features.
The aim is not simply to find the mortgage that allows you to borrow the most, but to understand which option fits your circumstances and plans.
6. Application and Ongoing Support
Once you have decided how you would like to proceed, we help with the mortgage application and supporting paperwork.
We then continue to support you through the process towards completion.
You Do Not Need to Know Everything Before You Speak to Us
You do not need to understand every mortgage term, know exactly how much you can borrow or have everything worked out before your first conversation.
Our job is to understand where you are now, where you want to get to and then help you work out the most appropriate route to get there.
Why Choose Everest Mortgages for Your Teacher Mortgage?
Choosing a mortgage broker is about more than finding a mortgage rate.
At Everest Mortgages, we have more than 14 years of mortgage industry experience and have arranged more than 1,000 mortgages across a wide range of circumstances.
We have also arranged lots of mortgages for teachers and education professionals, giving us experience with the different employment situations that can arise within the education sector.
We are 100% independent with no lender ties, which means we are not restricted to one particular lender’s mortgage products.
Our whole-of-market knowledge allows us to consider a broad range of lending criteria when looking at your circumstances. This can be particularly valuable for teachers, as different lenders may assess education-sector income, employment arrangements and affordability in different ways. Where appropriate, we can also consider specialist lender criteria that may offer higher borrowing for eligible applicants.
Everest Mortgages is FCA regulated, and John Everest is CeMAP qualified.
We also bring property experience alongside mortgage expertise. John has personally bought and developed property and has experience of the wider property purchase process, not just the mortgage itself.
As a Brighton-based mortgage broker, we understand the local area and work with clients across Brighton, East Sussex and West Sussex.
For more about John’s background and property experience, see our John Everest profile.
You can also learn more about our wider mortgage advice through our Mortgage Broker Brighton.
FAQs
Frequently asked questions
If you are considering a mortgage as a teacher or education professional, you may have questions about borrowing, eligibility and how different employment situations can affect your application. Here are some of the questions we are asked most often.
Can teachers get a mortgage?
Yes. Teachers can apply for mortgages just like other homebuyers. The amount you can borrow and the mortgage options available will depend on your income, deposit, expenditure, employment circumstances and the lender’s criteria.
How much can a teacher borrow?
There is no single amount that applies to every teacher. Your borrowing capacity depends on your income, financial commitments, deposit, employment circumstances and the lender’s affordability assessment.
Different lenders may also assess teacher income and employment circumstances differently, so the amount one lender is prepared to offer may not be the same as another.
Can teachers borrow 7 times their income?
Some eligible teachers and education professionals may be able to borrow up to 7 times their income through specialist lending, subject to the relevant lender criteria and affordability assessment. It is not available from every lender and does not mean every teacher will qualify for the maximum multiple.
Can newly qualified teachers get a mortgage?
Potentially, yes. Some lenders have specialist criteria for Early Career Teachers and newly qualified teachers, including applicants who are starting a new teaching role. The criteria vary between lenders.
Can supply teachers get a mortgage?
Yes. Supply teachers can get a mortgage, including those working through agencies or across multiple schools. Lenders may assess your income history, regularity of work and employment arrangements. You may need to provide agency payslips, bank statements and evidence of previous or ongoing assignments. The criteria vary between lenders.
Can teachers on fixed-term contracts get a mortgage?
Yes. Some lenders accept teachers on fixed-term contracts. They may consider how long remains on your current contract, your previous employment history and whether further work is likely. A permanent contract is not always necessary, but you will need to meet the lender’s income and affordability requirements.
Can teaching assistants get a mortgage?
Yes, teaching assistants can apply for mortgages. Your borrowing capacity will depend on your income, deposit, expenditure and the lender’s criteria.
Can I get a teacher mortgage with a small deposit?
Some mortgage products may be available with smaller deposits, but the deposit required will depend on the lender, product and your individual circumstances. A mortgage broker can help you understand the options available.
Can my partner apply with me if they are not a teacher?
Potentially, yes. Some specialist lenders allow joint applications where only one applicant works in education. The exact criteria vary between lenders.
Can Everest Mortgages help teachers in East Sussex and West Sussex?
Yes. Everest Mortgages is based in Brighton and works with clients across East Sussex and West Sussex, as well as elsewhere in the UK.
Ready to Explore Your Teacher Mortgage Options?
Being a teacher does not mean you need a specialist mortgage to buy a home. However, different lenders can have different criteria for teacher income, employment arrangements and affordability.
If you want to understand how much you could potentially borrow or which mortgage options may be available to you, Everest Mortgages can help.
As an independent, whole-of-market mortgage broker, we can look across a wide range of lenders and help you understand which options may be suitable for your circumstances.
Thinking about buying a home or remortgaging? Book your free mortgage consultation with Everest Mortgages and let’s discuss your circumstances.
Mortgage Disclaimer
Your home may be repossessed if you do not keep up repayments on your mortgage.
The availability of mortgage products, lending criteria, income multiples and interest rates can change. Any income multiple or borrowing figure mentioned on this page is subject to the relevant lender’s criteria, affordability assessment and individual circumstances.
Everest Mortgages can explain your options and help you understand which mortgage products may be suitable for your circumstances.