
Quick Answer
You do not always need the divorce to be finalised before speaking to a mortgage broker, but lenders usually need clarity before completion. A financial consent order can be important because it records the agreed financial settlement. Mortgage advice and legal advice should work together.
Divorce Settlement and the Family Home
We often see people trying to finalise divorce arrangements while still unsure what will actually happen with the family home once a lender gets involved. On paper, the numbers may look workable, but in reality affordability checks, existing mortgage commitments and changing household income can quickly reshape what is possible.
This guide is designed to help you step through the key mortgage and legal considerations before you finalise any settlement decisions. We’ll look at when to speak to a broker, how legal agreements and mortgage requirements interact, and why the order of decisions matters more than most people realise.
In many cases across Brighton, Hove, Worthing, Shoreham, Lewes and wider Sussex, delays or unexpected outcomes happen not because the agreement is wrong, but because mortgage criteria haven’t been factored in early enough. Understanding both sides together can help reduce pressure later in the process and avoid revisiting decisions once legal paperwork is already underway.
We’re now going to walk through seven key mortgage and legal steps that typically come up when dealing with a divorce settlement and the family home. These are the points that can influence affordability, ownership options, and what a lender may be prepared to approve.
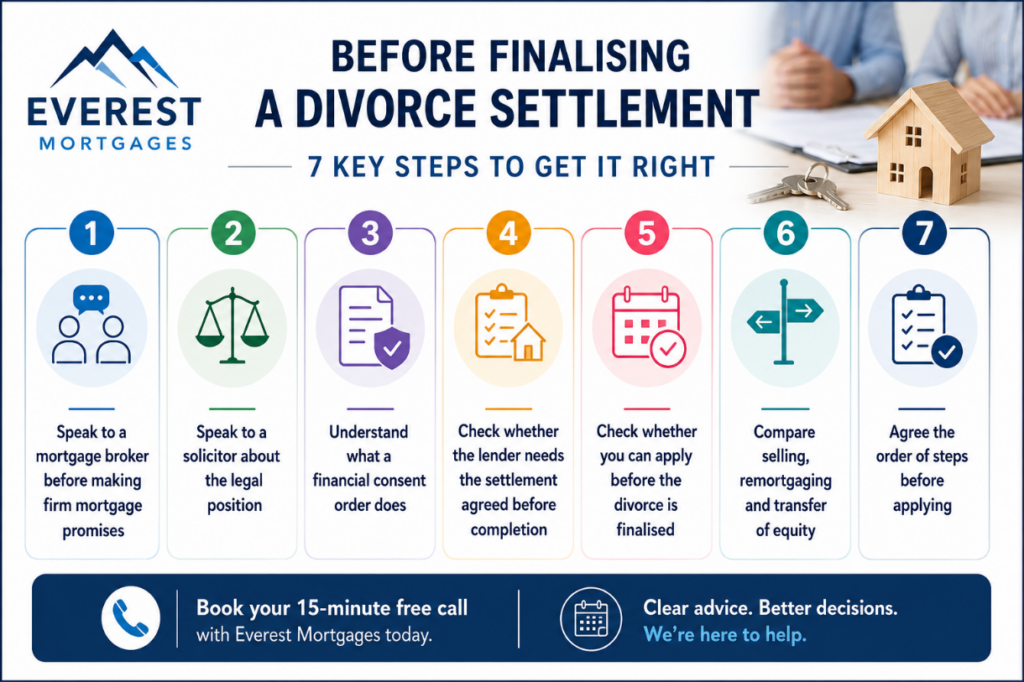
1. Speak to a Mortgage Broker Before Making Firm Mortgage Promises
Before agreeing that one person will keep the family home or buy out an ex-partner, it is important to check whether the mortgage is realistically affordable on one income.
Many separating couples agree figures too early without understanding how much they may actually be able to borrow after divorce. A lender will usually reassess affordability based on income, regular spending, existing financial commitments and the overall mortgage balance.
This is particularly important across Brighton, Hove and Lewes, where higher property values can create larger equity buyouts. The average house price in Brighton and Hove was around £403,000 in February 2026 according to the UK House Price Index.
What a Mortgage Broker Can Help Check
A mortgage broker can help assess:
- borrowing capacity on a single income,
- affordability after separation,
- whether child or spousal maintenance may be considered,
- transfer of equity options,
- and whether remortgaging may be possible subject to lender criteria.
Some lenders may also look closely at monthly childcare costs, existing loans or credit card commitments, outstanding joint debts, and any ongoing financial responsibilities that could affect affordability after separation.
Why Early Mortgage Advice Matters
Across Worthing, Shoreham and wider East and West Sussex, many couples discover that agreeing a settlement figure does not automatically mean the lender will approve the mortgage arrangement.
For example, a lender may still need to confirm:
- whether one person can afford the mortgage alone,
- whether additional borrowing is required,
- and whether the existing mortgage lender will allow one borrower to be removed.
Checking the mortgage position early may help avoid delays, unrealistic buyout agreements or problems later in the settlement process.
Before finalising a divorce settlement involving the family home, speak with Everest Mortgages. As a Brighton and Sussex-focused whole-of-market mortgage broker supporting clients across Brighton, Hove, Worthing and wider Sussex, Everest Mortgages can help you understand your mortgage options before agreements are finalised.
today
Find out how much you could borrow in minutes. No credit check, no commitment – just clear, honest mortgage advice.
2. Speak to a Solicitor About the Legal Position
Before agreeing who keeps the property, it is important to understand the legal position surrounding ownership, equity and future financial responsibility. In many divorce cases, the biggest issue is not simply whose name is on the mortgage, but:
- who legally owns the property,
- how much equity each person may be entitled to,
- and whether the home will be sold, transferred or retained.
Across Brighton, Hove and Lewes, rising property values have increased the size of equity discussions during separation. In February 2026, the average property price in Brighton and Hove was approximately £403,000 according to the UK House Price Index.
This can have a major impact on how much one person may need to pay to buy out the other’s share of the property. It can also affect the amount they may need to borrow and whether keeping the home is realistically affordable on a single income long term.
Transfer of Equity Does Not Automatically Remove Mortgage Liability
Many separating couples assume that transferring ownership removes both parties from the mortgage. In practice, these are usually two separate processes.
If one person keeps the home, a transfer of equity may change the legal ownership of the property, but the lender will still decide whether the remaining borrower can take over the mortgage alone.
This is where problems sometimes arise across Worthing, Shoreham and wider Sussex, particularly where:
- income has reduced after separation,
- the mortgage balance remains high,
- or joint debts still exist.
Questions around ownership disputes, forcing a sale or financial claims are legal matters and should be discussed with a solicitor based on your circumstances.
with a mortgage expert
- 15-minute call, no commitment
- Whole-of-market, FCA regulated
- Clarity and confidence in your next move
3. Understand What a Financial Consent Order Does
A financial consent order is a court-approved document that records the financial agreement reached during divorce. It can cover property, savings, pensions, maintenance and other shared finances.
Without one, financial claims between former spouses can sometimes remain open long after the divorce itself is finalised.
In England and Wales, the court fee for submitting a consent order application is currently around £60 as of 2026 (GOV.UK, 2026).
Why Timing Can Matter
A consent order is usually dealt with after the conditional order stage of divorce proceedings. However, mortgage discussions often begin much earlier, especially where one person wants to:
- keep the family home,
- remortgage,
- or buy another property before the divorce is fully completed.
That is why many separating couples across East and West Sussex speak to both a solicitor and mortgage broker early in the process so financial decisions can be coordinated properly.
number of lenders, including…


4. Check Whether the Lender Needs the Settlement Agreed Before Completion
It may be possible to apply for a mortgage before the divorce is legally finalised, depending on your circumstances.
However, lenders will usually want clarity around any financial commitments that could affect affordability or future liability. For example, lenders may ask for evidence showing:
- where the deposit is coming from,
- whether equity from a property sale has been agreed,
- whether maintenance payments are formalised,
- and whether existing joint mortgage commitments will continue after completion.
A recurring issue in divorce mortgage cases is that one person is still legally tied to the existing mortgage while trying to apply for a new one simultaneously.
Existing Financial Liabilities Still Matter
Some lenders may treat the current joint mortgage as an ongoing commitment until the property is sold or the mortgage is formally transferred into one name. This can reduce borrowing capacity, particularly where:
- childcare costs have increased,
- maintenance payments are ongoing,
- or unsecured debts remain in joint names.
Recent discussions across UK mortgage forums also show that lenders do not always require a sealed consent order before issuing a mortgage offer, but they often assess the wider financial picture carefully where divorce-related liabilities still exist.
Delays Often Happen When Financial Steps Are Taken in the Wrong Order
Across Brighton, Hove, Worthing and wider Sussex, delays often happen when separating couples begin mortgage arrangements before key financial details have been fully agreed. Common problems include uncertainty around the property sale, unclear equity figures or situations where one person expects to come off the mortgage before the lender has approved the change
Checking lender requirements early can help separating couples understand whether the proposed settlement is likely to work from a mortgage perspective before legal agreements are finalised.
by the FCA
No lender ties


5. Check Whether You Can Apply Before the Divorce Is Finalised
Many people assume they must wait until the divorce is fully completed before speaking to a lender or applying for a mortgage. In reality, that is not always the case.
Some mortgage applications can move forward during separation or while divorce proceedings are ongoing, especially if the financial situation is relatively clear.
However, lenders usually want to understand what financial commitments will still exist after the separation.
Joint Mortgages Can Still Cause Problems
One of the biggest issues is that many people remain financially linked to their ex-partner while trying to apply for a new mortgage.
If your name is still on a joint mortgage, most lenders will continue treating that payment as your responsibility, even if you no longer live in the property. This can reduce how much you may be able to borrow, particularly if:
- the existing mortgage balance is high,
- maintenance payments are involved,
- or household income has dropped after separation.
Delays Often Happen When Finances Are Still Unclear
Mortgage applications tend to become more complicated when important details are still unresolved. For example, delays can happen where:
- equity from the family home has not yet been released,
- the property sale is still being negotiated,
- or there are ongoing disputes about who will keep the property.
Across Brighton, Hove and wider Sussex, this is particularly common where higher property values mean larger equity amounts are tied up in the home.
Some lenders may also ask for extra documents if the separation is still ongoing, especially where maintenance income, joint liabilities or future housing arrangements are not fully settled yet.
Before making major decisions during divorce, it can help to understand how lenders are likely to assess your situation based on your current financial commitments rather than waiting until problems arise later.
If you are unsure whether you can apply for a mortgage before the divorce is finalised, Everest Mortgages can help you understand how lenders may assess joint mortgages, ongoing financial commitments and unreleased equity during separation.
you borrow?
Whether you’re employed, self-employed, or a limited company director — get a realistic borrowing range in under 60 seconds. No personal details required.
6. Compare Selling, Remortgaging and Transfer of Equity
Selling the Property
For some separating couples, selling the home is the cleanest financial option, especially where neither person can comfortably afford the mortgage alone. Selling the property can release the equity tied up in the home and repay the existing joint mortgage at the same time. For some separating couples, this can make it easier to separate finances completely and move forward independently.
This is often considered where there are ongoing affordability concerns or disagreements about who should keep the property.
Across Brighton, Hove and Lewes, higher property values can sometimes create substantial equity after a sale. The average house price in Brighton and Hove was around £403,000 in February 2026 according to the UK House Price Index. However, selling is not always straightforward. Some couples delay because:
- children are still living in the family home,
- the local rental market is expensive,
- or one person wants to remain in the property long term.
Remortgaging into One Name
Remortgaging may be possible where one person wants to keep the home and can meet lender affordability checks independently. This usually means one person takes responsibility for the existing mortgage while applying in their sole name after separation. In some cases, additional borrowing may also be needed to buy out an ex-partner’s share of the equity.
In areas such as Worthing and Shoreham, where property values may still remain relatively high compared with incomes, affordability can become the deciding factor rather than the amount of equity available.
For example, the average house price in Worthing was around £308,000 in early 2026 (ONS, Feb 2026). Even where there is enough equity, some borrowers may still struggle to meet lender affordability requirements after separation due to:
- reduced household income,
- childcare costs,
- maintenance commitments,
- or existing debts.
Transfer of Equity
A transfer of equity changes the legal ownership of the property, usually by removing one person from the title deeds. This option is commonly used where:
- one person keeps the home,
- both parties agree on the equity split,
- and the lender is prepared to approve the arrangement.
However, a transfer of equity does not automatically solve the mortgage side of the process. If the remaining borrower cannot meet lender criteria alone, the lender may refuse to release the other person from the mortgage.
Across East and West Sussex, this is one of the most common issues separating couples face when trying to keep the family home after divorce.
Which Option Is Best?
There is no single solution that works for everyone. The right option usually depends on:
- affordability after separation,
- the amount of available equity,
- future housing plans,
- and whether both parties agree on the next steps.
If you are unsure whether selling, remortgaging or transfer of equity may be more suitable, Everest Mortgages can help you understand how lenders may assess your options across Brighton, Hove, Worthing and wider Sussex before major decisions are finalised.
Your home may be repossessed if you do not keep up repayments on your mortgage.


7. Agree the Order of Steps Before Applying
One of the biggest causes of delay during divorce mortgage cases is taking steps in the wrong order. Many people focus on the legal settlement first, only to later discover that the proposed mortgage arrangement may not meet lender criteria. Others apply for a mortgage too early before equity, ownership or affordability figures are fully clear. A more structured approach can help reduce delays and avoid unnecessary financial pressure.
A Practical Order That Often Works Better
In many cases, separating couples find it helpful to work through the process in stages:
- check mortgage affordability with a broker,
- confirm the property value and outstanding mortgage balance,
- obtain legal advice regarding ownership and settlement,
- agree the proposed equity split,
- check lender requirements,
- prepare supporting documents,
- submit the mortgage application,
- then complete the legal work.
This approach can help identify affordability problems early before legal agreements are finalised.
Why Property Values Matter Early in the Process
Across Brighton, Hove and Lewes, even relatively modest percentage differences in property value can significantly change equity calculations because property prices remain comparatively high.
Recent market data shows median property values in Hove remain above £400,000 in many areas during 2026. That means even relatively small differences in the property valuation can change how much one person may need to pay to buy out the other’s share. It can also affect the amount of deposit available and how much additional borrowing may be required from the lender.
Try to Resolve Mortgage Questions Before Legal Completion
Mortgage delays often happen when:
- documents are missing,
- affordability has not been checked early enough,
- or one person assumes lender approval will automatically follow the legal settlement.
Across Worthing, Shoreham and wider Sussex, separating couples who organise the mortgage side earlier often find the overall process more manageable and less stressful.
Before applying for a mortgage during divorce or separation, Everest Mortgages can help you understand the likely lender requirements, affordability position and next steps before legal completion takes place.
Your home may be repossessed if you do not keep up repayments on your mortgage.
- Totally impartial — we work for you, not the lender
- Whole-of-market access to thousands of deals
- Flexible appointments — evenings & weekends available
- We handle all the paperwork & lender negotiations
- FCA regulated — your advice is always protected
perfect mortgage?
Get in touch for a free, no-obligation consultation with one of our expert advisers. We’ll do all the hard work for you.
Get in TouchLegal Caution: Forcing a Sale and Ownership Disputes
Questions about forcing the sale of a property, ownership rights or disagreements over the financial settlement are legal matters and should always be discussed with a solicitor based on your circumstances.
For example, whether one person can force the sale of the family home will usually depend on factors such as legal ownership, divorce proceedings, children living in the property and any court decisions already in place.
From a mortgage perspective, the key issue is usually whether one person can realistically afford to take over the mortgage on their own and whether the lender is prepared to approve the arrangement subject to affordability and lender criteria.
This article is intended as general information only and does not constitute legal advice.
Speak to Everest Mortgages Before Finalising a Divorce Settlement
Before agreeing a property settlement, transfer of equity or remortgage during divorce, it helps to understand what may realistically be possible from a lender’s perspective. Mortgage affordability, joint liabilities, maintenance income and property equity can all affect the options available after separation.
Everest Mortgages supports clients across Brighton, Hove, Worthing, Shoreham, Lewes and wider Sussex with practical whole-of-market mortgage advice during divorce and separation.
Book your free 15-minute call to discuss your mortgage options before finalising legal agreements or making long-term decisions about the family home.
FAQs
1. Do I need a financial consent order before sorting out a mortgage?
Not always, but it can help clarify how assets, including the family home, are being divided. From a mortgage point of view, lenders mainly focus on affordability and liabilities, but having a clear financial agreement in place can make the overall process smoother when applying or remortgaging.
2. Do I need a solicitor before speaking to a mortgage broker?
You don’t necessarily need to speak to a solicitor first, but many people find it useful to understand both sides early. A mortgage broker can check affordability and lender criteria, while a solicitor deals with legal settlement, ownership and divorce arrangements.
3. Can I apply for a mortgage before the divorce is finalised?
Yes, in some cases you can apply while the divorce is still in progress. However, lenders will still assess your current financial situation, including joint commitments, income changes and ongoing liabilities, before making a decision.
4. Can one person force a sale of the house?
This is a legal matter and depends on ownership, court orders and individual circumstances. A solicitor should advise on whether a sale can be enforced. From a mortgage perspective, the focus is usually on whether one person can afford to take over or refinance the property.
5. Is it better to sell or remortgage during divorce?
It depends on affordability, equity, and future plans. Selling can provide a clean financial break, while remortgaging may allow one person to stay in the home if they can meet lender criteria. In some cases, a transfer of equity may also be an option if approved by the lender.