
Teacher remortgages
Find your perfect mortgage
Whole-of-market advice from a qualified broker – we search every lender to find your best deal.
Qualified Mortgage Adviser & Founder
As featured in


FCA
regulated
Fully authorised & regulated
by the FCA
100%
independent
Whole-of-market access.
No lender ties
1000+
mortgages arranged
for happy clients
Facts at a Glance
- Teachers can explore remortgage options, subject to lender criteria and affordability checks.
- Reviewing your mortgage before your current deal ends can help you plan ahead.
- Your income, credit history, outstanding balance and property value may affect your options.
- Newly qualified, supply and fixed-term teachers may have options depending on their circumstances.
- Remortgaging can involve fees and early repayment charges.
- Everest Mortgages offers independent, whole-of-market mortgage advice.
Takes under 3 minutes
Get your mortgage in principle
today
today
Find out how much you could borrow in minutes. No credit check, no commitment — just clear, honest mortgage advice.
Get my mortgage in principle
→
Free review · No credit checks · No obligation
If your current mortgage deal is ending or your financial circumstances have changed, it may be time to explore your remortgage options. Teachers can remortgage, subject to lender criteria, affordability checks and the terms of the existing mortgage. Remortgages for teachers can be worth reviewing if you want to change your rate, term or borrowing.
You might want to check your interest rate, change your mortgage term or explore additional borrowing for home improvements. The right option will depend on your outstanding mortgage, property value, income and financial commitments. Remortgaging is not simply about finding the lowest advertised rate. Fees, repayment terms and the overall cost of switching can all affect whether a new deal is suitable.
At Everest Mortgages, we help teachers explore mortgage options based on their individual circumstances and plans. Explore our Teachers’ Mortgages guide for more information about mortgage options for education professionals.
Why Might a Teacher Consider Remortgaging?
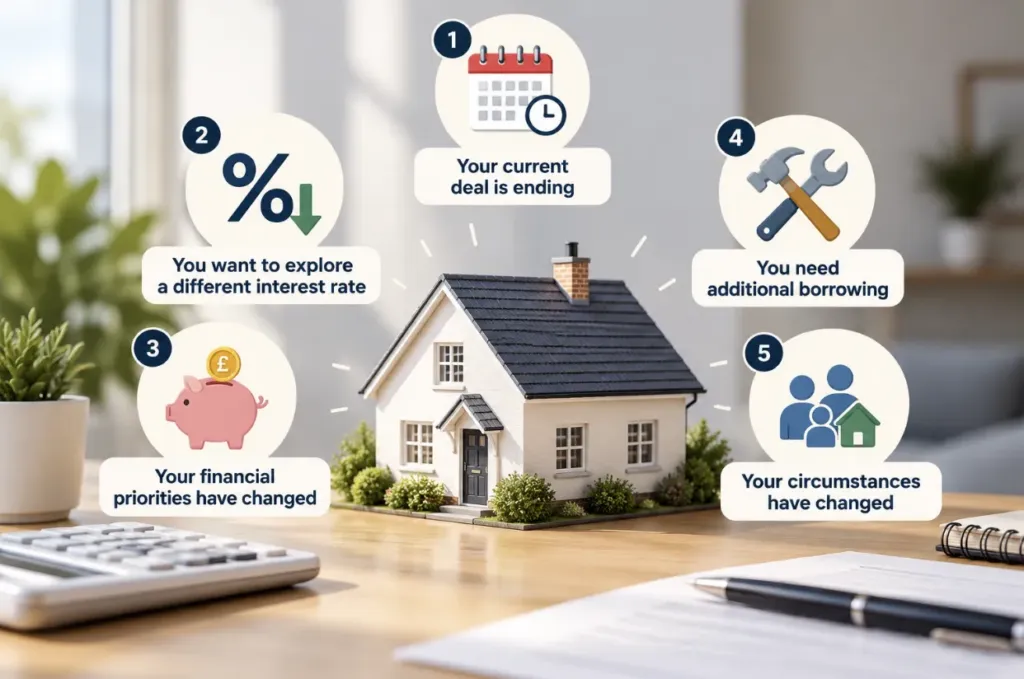
There are several reasons teachers may consider remortgaging.
- Your current deal is ending. If your fixed-rate or introductory deal is approaching its end date, reviewing your options may help you decide what to do next.
- You want to explore a different interest rate. Depending on the products available and your circumstances, another mortgage deal may offer more suitable terms.
- Your financial priorities have changed. You might want to adjust your mortgage term or explore whether your repayments can better fit your current budget.
- You need additional borrowing. If you are planning home improvements or another eligible expense, you may be able to explore borrowing against your property, subject to affordability and lender criteria.
- Your circumstances have changed. Changes in income, employment or household commitments may affect which mortgage options are suitable.
Remortgaging does not automatically mean lower repayments or savings. Compare the full costs and terms before deciding whether to switch.
We search 1000's of mortgage deals across a large number of lenders, including...


When Should Teachers Start Looking at Remortgage Options?
It is worth checking your mortgage deal’s end date early so you have time to consider your options before it expires.
Start by reviewing your current mortgage documents to understand when your deal ends, whether an early repayment charge applies and what rate you may move onto afterwards. You can then compare the options available from your existing lender with potential deals from other lenders. This gives you time to consider the interest rate, fees, eligibility requirements and application process.
If you are considering switching lenders, you may need to provide income evidence and undergo affordability and credit checks. The lender may also need to value your property. There is no single timeframe that suits every borrower. Starting early gives you more time to compare options and check when a new deal can begin.
Should You Remortgage or Stay With Your Current Lender?
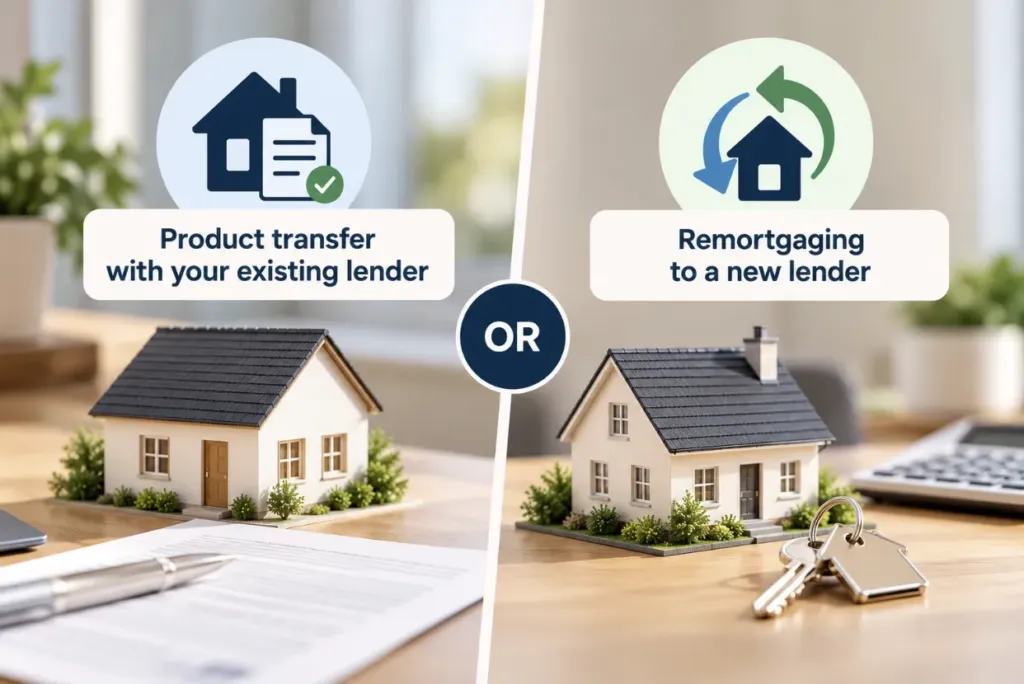
When reviewing your mortgage, you generally have two main options: moving to a new deal with your current lender or applying for a mortgage with a different lender.
Product transfer with your existing lender
A product transfer means moving to another mortgage deal with your current lender. Depending on the lender and product, this typically does not require a full new affordability reassessment or property valuation. It can therefore involve less paperwork and be quicker than switching lenders, although requirements vary.
Remortgaging to a new lender
Switching lenders involves applying for a new mortgage. This usually includes a new affordability assessment, credit checks and a property valuation, although the exact process depends on the lender. You may also need legal work to transfer the mortgage.
A new lender may offer products that better suit your circumstances, but switching can involve additional fees and administration.
Neither option is automatically better. Compare the interest rate, fees, early repayment charges and overall cost before deciding which option suits your circumstances.
Read our reviews
Can Teachers Get Better Remortgage Rates?
Teacher remortgage rates depend on the deals available and your circumstances. Being a teacher does not automatically guarantee a lower rate.
Lenders may consider several factors when assessing an application:
- Loan-to-value (LTV): The amount you owe compared with your property’s value.
- Income and affordability: Whether your income supports the proposed repayments.
- Credit history: Your record of managing credit and repayments.
- Existing commitments: Loans, credit cards and regular household expenses.
- Mortgage term and fees: The repayment period and costs associated with the product.
A lower advertised interest rate does not necessarily mean a cheaper mortgage overall. Product fees, legal costs and early repayment charges can affect the total cost of switching. It is also important to consider whether the repayments fit your budget, rather than choosing a deal based on its rate alone.
Comparing suitable options can help you understand which deal best fits your circumstances and budget.
For current market context, read our Should You Remortgage Now? guide or our UK Mortgage Rates: October 2026 article.
Trusted mortgage advice
Why choose Everest Mortgages?
Independent, whole-of-market advice from advisers who put you first — every time.
🛡️
Advisers you can trust
We're totally impartial and focused on finding the perfect mortgage to suit you — not the lender.
🔍
We search the market for the best deals
We work with all lenders, big and small, to give you exclusive access to a comprehensive range of mortgage rates.
🗓️
We work to your schedule
We're flexible to fit around you — evenings, weekends, whatever works best for your life.
✨
We take away the hassle
We deal with lenders on your behalf, so everything from paperwork to negotiation is completely stress-free.
🤝
We're supportive and friendly
Our highly experienced advisers make the entire buying process painless by taking all the work off your hands.
John Everest
Qualified Mortgage Adviser & Founder
Book a free consultation with a mortgage expert
John is a CeMAP-qualified, whole-of-market mortgage adviser and Director of Everest Mortgage Services. With over 21 years in financial services, and a track record of 1,000+ mortgages arranged.
- 15-minute call, no commitment
- Whole-of-market, FCA regulated
- Clarity and confidence in your next move
14+
Years experience
1,000+
Mortgages arranged
Mortgage tools
Find out how much you can borrow
Use our free calculator to get an instant estimate based on your income — no credit check, no commitment.
💰
How much can I borrow?
Applicant 1
Applicant 2
💰
Your results
Director note: Limited company directors can use dividends or shares on net profits to obtain their affordability.
Enter your details for an accurate range.
Estimated borrowing
Low (4.5x)
£0
Medium (5x)
£0
High (6x)
£0
Need the maximum loan possible?
Specialist lenders may go higher.
Free consultation
Ready to find your perfect mortgage?
Get in touch today and one of our qualified advisors will be in touch to guide you through your options.
✓
Free, no-obligation advice
No cost to speak with a qualified adviser.
🔒
No credit checks
Your credit score won't be affected.
⚡
Fast response
We aim to get back to you within 2 hours.
🏛️
FCA regulated
Fully authorised and regulated by the FCA.
How Much Can a Teacher Borrow When Remortgaging?
Remortgage affordability for teachers depends on income, financial commitments, property value and the lender’s criteria. Lenders may assess your current income, accepted additional income, existing debts, regular expenses, credit history and proposed mortgage term. If you want to borrow more than your outstanding mortgage balance, they will also consider the purpose of the additional borrowing.
Your equity is broadly the difference between your property’s value and the amount remaining on your mortgage. For example, if your property is worth £300,000 and your outstanding mortgage is £180,000, your equity would be £120,000 before any relevant costs.
However, having equity does not automatically mean you can borrow against all of it. The lender must assess affordability, its maximum loan-to-value (LTV) limits and any requirements linked to the purpose of the borrowing.
Want to explore your options? Use our Mortgage Calculator to get an initial estimate and help you plan your next steps. The amount you could borrow will depend on the lender’s assessment of your circumstances.
What If You’re a Newly Qualified, Supply or Fixed-Term Teacher?
Your employment arrangements may influence how a lender assesses your remortgage application, but they do not automatically rule out your options.
Newly qualified teachers: If you have recently started a teaching role or your income has changed, lenders may consider your confirmed employment, current income and employment history.
Supply teachers: If you work through an agency or have variable hours, lenders may want evidence of how your income is earned and how consistent it has been.
Fixed-term and contract teachers: Lenders may consider your current contract, employment history, previous renewals and income when assessing affordability.
Each lender has different criteria, so the evidence required and options available will depend on your circumstances. If your employment has recently changed, preparing the relevant documents can help you understand what may be possible.
For more detail, explore our dedicated guides:
What Costs Should Teachers Consider Before Remortgaging?
Before switching mortgage deals, consider the costs involved, as these can affect whether remortgaging offers good value.
- Early repayment charges: Your current lender may charge a fee if you leave your existing deal before the permitted date.
- Product or arrangement fees: Some new mortgage deals include a fee, while others do not.
- Valuation fees: A new lender may need to assess the property’s value, although some products include the valuation.
- Legal fees: Switching lenders may involve conveyancing work, depending on the mortgage and lender.
- Other administration or exit fees: Your existing mortgage terms may include additional charges.
Some lenders cover certain costs as part of a remortgage product, while others charge separately. A deal with a lower interest rate may not be the cheapest overall once fees are included. Compare the total cost over the period you expect to keep the deal, including any charges for leaving your current mortgage.
How Can Teachers Prepare for a Remortgage Application?
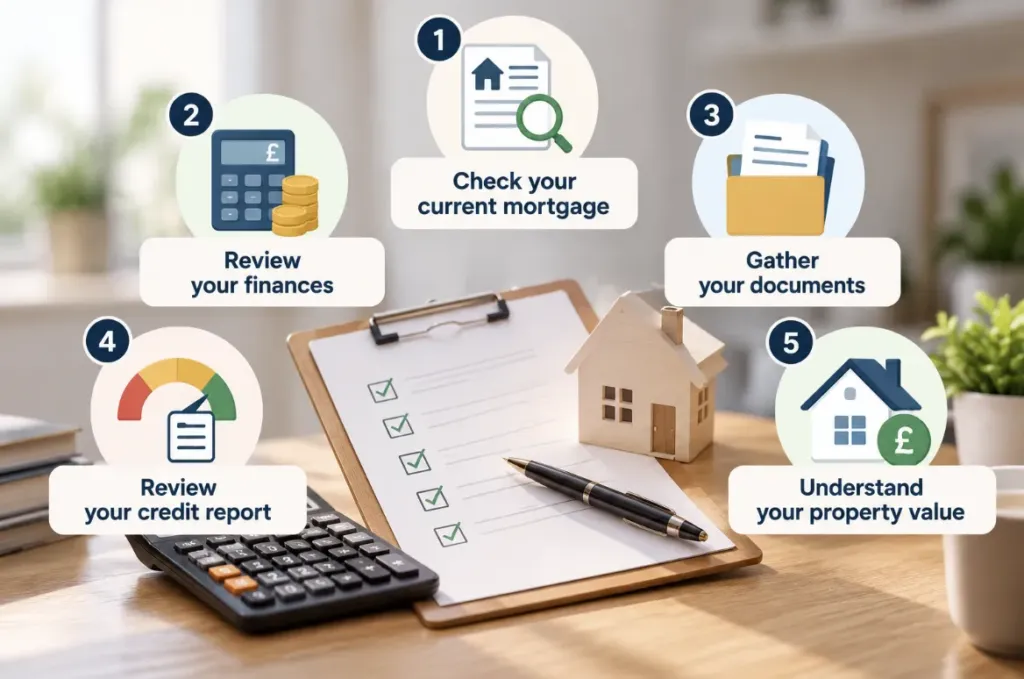
Preparing your information before applying can make it easier to discuss your options with an adviser.
- Check your current mortgage. Confirm your outstanding balance, interest rate, deal end date and any early repayment charges.
- Review your finances. Look at your income, regular expenses, existing borrowing and the monthly repayment you could comfortably manage.
- Gather your documents. Recent payslips, bank statements, identification and other income evidence may be required. If you work on supply or a fixed-term contract, additional employment information may be requested.
- Review your credit report. Check for errors and address any inaccuracies through the relevant credit reference agency.
- Understand your property value. An estimate can help with initial discussions, although a lender may use its own valuation.
Finally, decide what you want from the remortgage. Whether your priority is reviewing your interest rate, changing the term or borrowing more, understanding your objective can help you compare relevant options.
Case Study
A Teacher Reviewing Their Mortgage Options
Deal approaching its end date
→
A clear comparison of the options and costs
Hover over each stage to follow the journey
Stage 01
The Challenge
A teacher’s current mortgage deal was approaching its end date, prompting them to review their options before moving onto a different rate. They wanted to understand whether staying with their existing lender or switching providers would be more suitable.
With household expenses to manage, it was important to consider not just the interest rate but also the potential fees and monthly repayments associated with a new deal.
Stage 02
Our Approach
Everest reviewed the teacher’s circumstances, including their outstanding mortgage balance, income, regular commitments and plans for the property. The available product-transfer and remortgage options were then considered against the relevant lender criteria.
By looking at the overall costs and terms rather than focusing on the headline rate alone, the teacher could better understand the differences between the available routes.
Stage 03
The Outcome
The teacher gained a clearer understanding of the options available and the costs to consider before their current deal ended.
This helped them make a more informed decision about the next stage of their mortgage, with greater clarity around how the potential repayments would fit their household budget.
Stage 04 · Broker Insight
What Should Teachers Check Before Remortgaging?
One important consideration when reviewing a mortgage is the overall cost of switching, rather than just the interest rate. A new deal may appear attractive, but product fees, legal costs and early repayment charges can affect its value.
Teachers should also consider whether the proposed repayments fit their current budget and whether their circumstances have changed since they first took out the mortgage.
Starting the review early can provide more time to compare a product transfer with deals from other lenders, understand the requirements and make a considered decision.
How Does the Teacher Remortgage Process Work?
The remortgage process generally follows these stages:
- Review your existing mortgage: Check your balance, deal end date and any applicable charges.
- Discuss your circumstances: Explain your income, commitments and reasons for remortgaging.
- Compare options: Consider suitable product transfers and mortgages from other lenders.
- Review affordability and costs: Check the repayments, fees and relevant lender criteria.
- Submit an application: Provide the required information and supporting documents.
- Complete the process: The lender carries out its checks and any required legal work before the new mortgage begins.
The process varies depending on the lender, product and whether you want to borrow more. An agreement in principle or mortgage illustration is not a guarantee of final mortgage approval.
Partner offer
See your credit file from all 3 agencies
Everest Mortgage Services has an affiliate relationship with Checkmyfile. Try it free for 7 days and spot any issues before a lender does.
Experian
Equifax
TransUnion
Start my 7-day free trial
→
7 days free, then £14.99 a month · Cancel anytime
Why Use a Mortgage Broker as a Teacher?
A teacher mortgage broker can help you understand which lenders may consider your circumstances and compare relevant remortgage options. This can be useful if your income or employment arrangements have changed, or if you are deciding between a product transfer and switching lenders. A broker can also help you consider fees, affordability, mortgage terms and any additional borrowing requirements.
Everest Mortgages offers independent, whole-of-market mortgage advice, helping teachers explore available options based on their individual circumstances. The aim is to help you make an informed decision rather than assume that the lowest advertised rate will always be the most suitable choice.
If your current deal is ending, speaking to an adviser can help you understand the information needed and the options worth considering.
Visit our Teachers’ Mortgages guide to explore further guidance.
FAQs
Frequently asked questions
If you’re considering remortgaging as a teacher, you may have questions about timing, affordability and the options available to you. Here are answers to some common questions to help you understand your next steps.
Can teachers remortgage?
Yes. Teachers can explore remortgage options, subject to lender criteria and affordability checks. The available products will depend on factors such as income, credit history, outstanding mortgage balance and property value.
When should teachers start looking at remortgage deals?
It is useful to check your current deal’s end date early. This gives you time to compare options, understand any charges and prepare the information needed for an application.
Can I remortgage before my current deal ends?
Potentially, but leaving your existing deal early may trigger an early repayment charge. Check your mortgage terms and compare the cost of switching early with the benefits of a new deal.
Will remortgaging reduce my monthly payments?
It may, depending on the new interest rate, mortgage term, fees and outstanding balance. However, lower monthly repayments do not always mean lower overall costs, particularly if the mortgage term is extended.
Can teachers remortgage with a different lender?
Yes. You can apply to a different lender, subject to its criteria and affordability assessment. Switching usually involves a new application and may require a valuation and legal work.
Can a supply teacher remortgage?
Potentially. Lenders may assess how your income is earned, its consistency and the evidence available. The options will depend on your circumstances and the lender’s criteria.
Can I remortgage on a fixed-term teaching contract?
Possibly. Some lenders may consider fixed-term employees, taking account of income, employment history and contract details. Eligibility and documentation requirements vary between lenders.
What fees should I check before remortgaging?
Check for early repayment charges, product fees, valuation fees, legal costs and any administration or exit fees. Compare the overall cost of the options rather than looking only at the interest rate.
Can Everest Mortgages help teachers in Brighton and Sussex?
Everest Mortgages can discuss your remortgage options and circumstances if you’re a teacher in Brighton, Sussex or the surrounding areas. Book your free consultation now to find out how we can support your remortgage plans.
Ready to Explore Your Mortgage Options?
If your current mortgage deal is ending or your circumstances have changed, Everest Mortgages can help you explore options based on your needs. Discuss your plans with the team to understand the factors affecting your remortgage and the next steps you could consider.
Disclaimer
This article is for general information only and does not constitute mortgage, financial, legal or tax advice. Mortgage eligibility, lending criteria, interest rates and product availability can change and depend on individual circumstances. Any mortgage is subject to lender assessment and approval. Your home may be repossessed if you do not keep up repayments on your mortgage.