Facts at a Glance
UK Mortgage Rates: October 2026
Bank Rate: 3.75%, held on 17 September
Next Bank of England decision: 5 November 2026
2-year fixed rate at 75% LTV: 5.74% average
5-year fixed rate at 75% LTV: 5.81% average
2-year variable rate at 75% LTV: 4.40% average
Standard Variable Rate: 7.24% average
Data checked:…
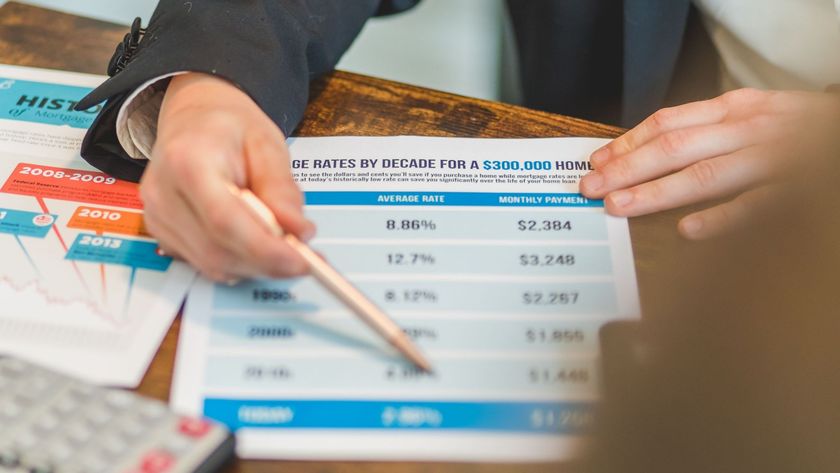
Having bad credit doesn’t mean you can’t own a home — but it can make the process a little more challenging. The good news is, with the right preparation and advice, getting a mortgage with bad credit in the UK is absolutely possible.
In this complete guide, we’ll explain what lenders look for, how to…
Quick Answer
A low credit score does not automatically rule out a mortgage, even if you have multiple debts. Start by checking all three credit reports, correcting errors, keeping repayments up to date and avoiding unnecessary new borrowing. Lenders use their own criteria and assess your wider finances, so the right mortgage option may depend…
Quick Answer
If your mortgage was declined because of bad credit, do not rush into another application. Find out why you were declined, check your credit reports, review your affordability and allow time for recent adverse credit to improve where necessary. You can then assess whether another lender's criteria may fit your circumstances or whether…
Buying a property already comes with plenty of expenses — from deposits and solicitor fees to surveys and moving costs. One of the biggest extra costs is Stamp Duty Land Tax (SDLT).
A common question homebuyers ask is: “Can I add stamp duty to my mortgage?”
The answer is: not directly, but there are ways…
Quick Answer
Yes, an offset mortgage could save you thousands, but it depends on how much you keep in savings, your mortgage rate, fees and how long the money remains offset. It can be particularly useful for borrowers with substantial cash savings, irregular income, regular bonuses or a large emergency fund. However, a higher offset…
Facts at a Glance
UK Mortgage Rates: Where Things Stand
Bank Rate: 3.75%, held on 17 September 2026 MPC vote: 6–3 to hold Bank Rate at 3.75% Average UK 2-year fixed mortgage rate: 5.92% Average UK 5-year fixed mortgage rate: 5.94% Fixed-rate mortgages due to expire in 2026: around 1.8 million Next Bank of England…
Quick Answer
Consolidating debt into your mortgage can reduce your monthly payments, but it can also increase the total interest you pay and turn unsecured debt into debt secured against your home. Before proceeding, check the full repayment cost, your loan-to-value ratio, any fees or charges, and whether a lower-risk alternative could be a better…
Facts at a Glance
Your First Home: What's Been Announced
Announced: 26 September 2026 by the Government
Who it's for: First-time buyers in England
Property type: New-build homes from participating developers
Deposit: As low as 2.5%
Government support: Up to a 20% government-backed equity loan
Interest: An initial interest-free period applies, although the length has…
Facts at a Glance
John Everest | Mortgage Broker, Everest Mortgages, Brighton 21 years in financial services · CeMAP-qualified, whole-of-market mortgage adviser · FCA-regulated · 15+ personal property purchases · Helped investors build portfolios from £0 to £20 million · Featured in national media
Quick Answer
I’m not just a mortgage broker. I’ve spent 21…
Quick Answer
Bad credit does not automatically stop you getting a mortgage. Missed payments, defaults, CCJs, completed DMPs, IVAs, discharged bankruptcy and even a previous repossession may be considered by some lenders depending on the type, age and severity of the issue, whether debts have been settled, your deposit, affordability and your credit conduct since.…
Quick Answer
Borrowing £25,000 or more against your home in Brighton and Hove can be a suitable option for home improvements, debt consolidation, or major expenses, but it also places your property at risk if repayments are not maintained.
Before proceeding, homeowners should assess affordability, total borrowing costs, loan-to-value impact, repayment strategy, and alternative financing…