Quick Answer
Remortgaging to release equity means replacing the current mortgage with a new mortgage, often for a higher amount, so the homeowner can access some of the value built up in the property. It may be used for home improvements, family support, debt consolidation or major expenses, but depends on affordability, property value, LTV, credit profile and lender criteria.
Remortgaging to Release Equity in Sussex
Many homeowners across Brighton, Hove, Worthing, Shoreham, Lewes and wider East and West Sussex have seen their property values rise over time, while steadily reducing their mortgage balance. That gap between the property’s value and the remaining mortgage is known as equity, and some homeowners choose to access part of it through a remortgage rather than selling their home.
Remortgaging to release equity means replacing your current mortgage with a larger one and receiving the additional borrowing as a lump sum. Depending on affordability, loan-to-value, credit profile and lender criteria, the money may be used for home improvements, supporting family, consolidating debts or covering major expenses. For Sussex homeowners with substantial equity tied up in their property, it can offer flexibility without moving home.
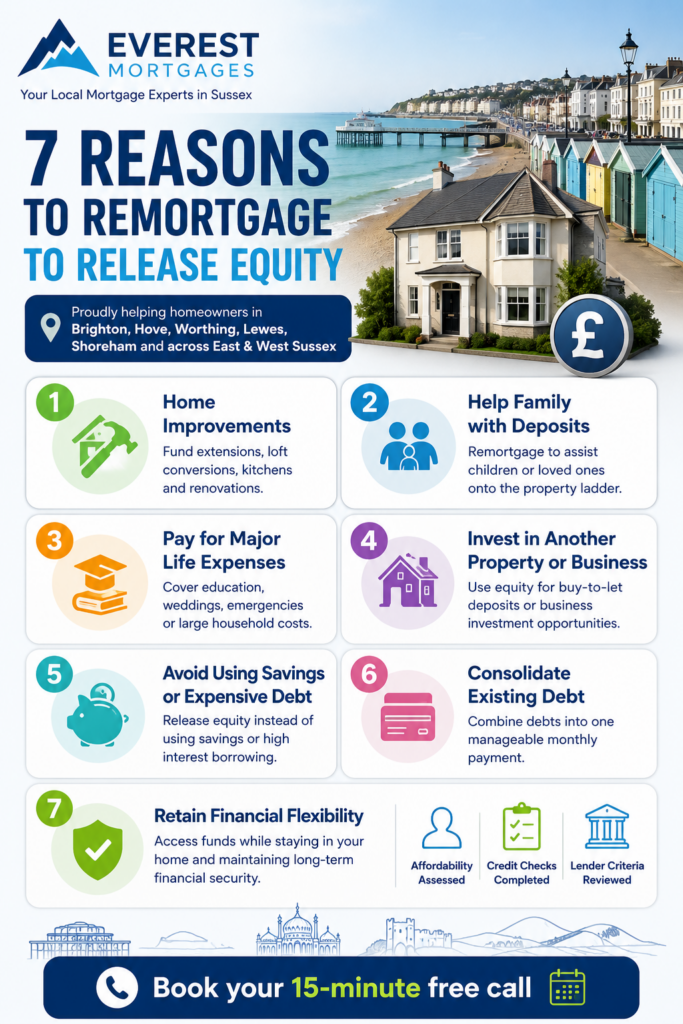
Below are seven common reasons homeowners in Brighton, Hove, Worthing, Lewes and wider East and West Sussex consider releasing equity through remortgaging.
1. To Fund Home Improvements
For many homeowners across Brighton, Hove, Worthing and wider Sussex, remortgaging to release equity is often linked to improving the home they already own rather than moving elsewhere. With moving costs, stamp duty and limited housing stock still affecting parts of East and West Sussex, some homeowners choose to invest in their current property instead.
Common Projects Sussex Homeowners Fund Through Remortgaging
Equity released through a remortgage may be used for:
- Kitchen renovations
- Loft conversions
- Rear or side extensions
- New windows and doors
- Structural repairs
- Roof replacement
- Insulation and energy-efficiency upgrades
- Rewiring or plumbing improvements
A mid-range UK kitchen renovation typically costs between £8,000 and £15,000, while larger bespoke projects can exceed £25,000 (Best Builders, 2026).
Loft conversions across the South East commonly range from around £45,000 to £80,000 depending on size and complexity (LoftCompare UK, 2026).
Why This Is Common in Sussex
In areas such as Lewes, Brighton and Hove, many older and period properties require ongoing modernisation. Meanwhile, family homes in Worthing and Shoreham are often extended to create additional living space instead of relocating.
Some homeowners also use remortgaging to improve EPC ratings through double glazing, insulation, heat pumps or solar upgrades, particularly as energy costs remain a concern.
Example Scenario
A homeowner in West Sussex owns a property valued at £450,000 with an existing mortgage of £250,000. They want to borrow an additional £50,000 for a loft conversion and kitchen refurbishment.
Their new mortgage would increase to £300,000, which equates to roughly 67% loan-to-value (LTV). Whether this is possible depends on affordability, income, credit profile, property value and lender criteria.
Important Considerations Before Borrowing More
Releasing equity for improvements may increase the property’s long-term value, but over-improving beyond local market ceilings can sometimes limit returns. This is particularly relevant in conservation areas across Brighton, Lewes and some coastal parts of Sussex where planning restrictions may apply.
At Everest Mortgages, we help homeowners across Brighton, Hove, Worthing, Lewes and wider Sussex compare whole-of-market remortgage options, assess borrowing limits and understand the long-term repayment costs before committing to major renovation projects.
Your home may be repossessed if you do not keep up repayments on your mortgage.
today
Find out how much you could borrow in minutes. No credit check, no commitment – just clear, honest mortgage advice.
2. To Extend or Modernise the Property
For many Sussex homeowners, remortgaging to release equity is less about adding space and more about making the property work better long term. In Brighton, Hove and Lewes, period homes often require structural updating, layout changes or modernisation to suit modern living. In Worthing and Shoreham, growing families may prefer extending their current home rather than facing the cost and disruption of moving.
Why Homeowners Choose to Modernise Instead of Move
Older Sussex properties can come with smaller kitchens, limited storage, outdated layouts or ageing interiors. Releasing equity through a remortgage may help fund:
- Open-plan reconfigurations
- Rear or side-return extensions
- Larger family kitchens
- Additional bathrooms
- Structural alterations
- Modern heating systems
- New flooring, windows and insulation
A standard 20m² extension in the South East typically costs between £45,000 and £65,000 in 2026, with higher-specification projects exceeding £90,000 depending on design and structural work required (Best Builders, April 2026).
Sussex Property Considerations
In conservation areas across Lewes and parts of Brighton and Hove, planning restrictions may affect what changes are possible. Victorian and Edwardian terraces may also require steelwork, drainage relocation or specialist materials, which can increase renovation costs.
Some homeowners also choose improvements that support long-term living, such as ground-floor layouts, wider access points or energy-efficiency upgrades.
Important Financial Considerations
While extending or modernising may improve lifestyle and potentially increase property value, larger projects can substantially increase borrowing and monthly mortgage costs. Lenders will assess affordability, property value, loan-to-value ratio and overall financial commitments before approving additional borrowing.
with a mortgage expert
- 15-minute call, no commitment
- Whole-of-market, FCA regulated
- Clarity and confidence in your next move
3. To Consolidate Debts Carefully
Some homeowners use remortgaging to release equity and repay higher-interest unsecured borrowing such as credit cards, personal loans or car finance. This can reduce monthly outgoings by moving several payments into one mortgage payment, often at a lower interest rate.
UK credit card borrowing rose by 12.1% annually in late 2025, reflecting increased reliance on unsecured borrowing as household costs continued to rise (The Guardian, 2025-2026).
How Debt Consolidation Through Remortgaging Works
A homeowner may choose to increase their mortgage balance to clear:
- Credit cards
- Personal loans
- Car finance agreements
- Overdrafts
- Store finance balances
For example, replacing unsecured borrowing charged at 20% to 30% interest with mortgage borrowing at a lower rate may reduce monthly payments significantly. However, mortgage borrowing is usually repaid over a much longer term.
The Long-Term Cost Matters
Lower monthly payments do not always mean lower overall borrowing costs. Extending debts over 20 or 25 years can increase the total amount repaid, even if the interest rate is lower.
Debt consolidation through remortgaging may simplify monthly payments, but spreading borrowing over a longer mortgage term could increase the total amount repaid. It is also important to remember that unsecured debts moved into a mortgage become secured against your home.
When Lenders May Be Cautious
Some lenders may carefully assess applications involving debt consolidation, particularly where there are:
- High existing credit commitments
- Recent missed payments
- Heavy credit utilisation
- Short-term financial pressure
- Multiple unsecured balances
Approval depends on affordability, income stability, credit profile and lender criteria.
For some Sussex homeowners, debt consolidation may improve monthly cash flow and simplify finances. However, it works best when combined with realistic budgeting and addressing the underlying cause of the borrowing rather than repeatedly increasing secured debt.
number of lenders, including…


4. To Help Children or Family with a Deposit
Rising property prices across Brighton, Hove, Worthing and much of the South East mean many first-time buyers now rely on family support to get onto the property ladder. Some Sussex homeowners choose to release equity through a remortgage to help children or grandchildren with a deposit while remaining in their current home.
UK Finance data shows the average first-time buyer deposit in the South East now exceeds £80,000 in some areas (UK Finance via Unbiased, 2026).
How Family Deposit Support Often Works
Equity released through a remortgage may be used to help with:
- First-time buyer deposits
- University or rental support
- Reducing a child’s mortgage borrowing
- Helping family remain in Sussex rather than relocating elsewhere
In Brighton and Hove particularly, where property prices remain high, family support can sometimes make the difference between buying locally and being priced out.
Gift or Loan? Lenders Will Want Clarity
When helping family with a deposit, lenders usually need confirmation whether the money is a non-repayable gifted deposit or a repayable family loan.
Gifted deposits are more commonly accepted by residential lenders, although each lender has different requirements. Some may ask for signed declarations confirming the funds do not create an interest in the property.
Important Long-Term Considerations
Releasing equity reduces the remaining equity held in your property and may affect future inheritance planning. Increasing mortgage borrowing can also increase monthly repayments into later life.
For some homeowners, helping family now is worth more than preserving future inheritance value. Others may prefer structured family loans or alternative arrangements.
Before releasing equity to help family members financially, speak with Everest Mortgages to understand how the additional borrowing could affect your monthly payments, future plans and long-term mortgage costs. Book your free 15-minute call to compare your options with a Sussex whole-of-market mortgage broker.
Your home may be repossessed if you do not keep up repayments on your mortgage.
by the FCA
No lender ties


5. To Pay for Major Life Expenses
Some homeowners remortgage to release equity for significant one-off costs that may be difficult to cover through savings alone. This can include education costs, weddings, family emergencies, large household expenses or other major financial commitments.
Unlike unsecured borrowing, remortgaging may allow larger sums to be borrowed over a longer term, although this also increases the amount secured against the property.
Common Reasons Homeowners Release Equity
Across East and West Sussex, released equity is sometimes used for:
- University or private education costs
- Weddings or family events
- Emergency financial support
- Care-related expenses
- Replacing vehicles or essential household items
- Lifestyle or retirement spending plans
Some homeowners also choose to provide ‘living inheritance’ support, helping family financially while they are still alive rather than later through their estate.
Borrowing Against Property Requires Careful Planning
While mortgage rates are often lower than unsecured borrowing, spreading costs over 20 or 25 years can substantially increase total repayment costs.
For example, borrowing £30,000 over a long mortgage term may reduce short-term monthly pressure, but interest remains payable for much longer compared with shorter-term finance options. Lenders will assess:
- Current income and affordability
- Age and mortgage term
- Existing debts and commitments
- Property value and loan-to-value ratio
- Credit profile and repayment history
Keeping an Emergency Buffer Matters
Some homeowners prefer releasing equity rather than exhausting savings completely, particularly where maintaining emergency reserves remains important. However, using secured borrowing for discretionary spending should always be considered carefully against long-term financial goals.
you borrow?
Whether you’re employed, self-employed, or a limited company director — get a realistic borrowing range in under 60 seconds. No personal details required.
6. To Invest in Another Property or Business
Some homeowners release equity through a remortgage to fund another investment opportunity rather than relying entirely on savings or separate finance. This may include purchasing a buy-to-let property, contributing towards a holiday let, funding a business venture or investing in an additional income stream.
Using Equity for a Buy-to-Let Deposit
In areas across Sussex, some homeowners use equity from their main residence as a deposit for:
- Buy-to-let properties
- Holiday cottages
- Coastal second homes
- Student rental investments
- Semi-commercial property purchases
For example, a homeowner in Worthing may release £70,000 equity from their residential property to use as a 25% deposit on a rental property elsewhere in the South East.
However, buying additional property now carries significantly higher upfront costs. Since late 2024, second homes and buy-to-let purchases in England have been subject to a 5% SDLT surcharge on top of standard stamp duty rates.
Business Investment and Self-Employment Funding
Some homeowners also remortgage to release equity for business purposes. This may include starting a new business, supporting cash flow in an existing company, purchasing equipment or funding expansion plans.
However, the borrowing becomes secured against the property. Lenders will normally review income, existing mortgage commitments, credit history, available equity and the sustainability of any self-employed earnings. Where funds are being used for business investment or higher-risk projects, some lenders may apply stricter affordability checks and lending criteria.
Investment Risks Should Be Considered Carefully
Rental income and property values can fluctuate, while business investments may not generate guaranteed returns. Landlord responsibilities, tax liabilities, maintenance costs and void periods should also be factored into affordability planning.
Speaking with both a mortgage broker and qualified tax adviser is often important before using residential equity for investment purposes.


7. To Avoid Using Savings or Expensive Unsecured Borrowing
Some homeowners choose to release equity through remortgaging to avoid depleting savings or relying on high-interest unsecured borrowing for large expenses.
This approach is often considered where homeowners want to preserve emergency funds while spreading costs over a longer repayment period.
Why Some Homeowners Compare Mortgage Borrowing
Credit card interest rates in the UK frequently exceed 20% APR, while unsecured personal loans can also carry significantly higher monthly costs depending on credit profile and loan size. Mortgage borrowing is often cheaper in monthly terms because it is secured against the property and repaid over a longer period.
This may make remortgaging appear more manageable for:
- Large home repairs
- Unexpected family expenses
- Temporary financial pressure
- Essential household spending
- Major planned purchases
Keeping Emergency Savings Intact
Some Sussex homeowners prefer not to exhaust cash savings completely, particularly during periods of economic uncertainty or approaching retirement. Maintaining accessible savings may help cover:
- Emergency repairs
- Income interruptions
- Family emergencies
- Rising living costs
- Unexpected care or medical expenses
Using property equity can sometimes provide flexibility while preserving part of those reserves.
Long-Term Borrowing Still Carries Risk
Although monthly payments may be lower than unsecured borrowing, extending debt across a long mortgage term can substantially increase the total amount repaid overall.
For example, borrowing £25,000 over 25 years through a mortgage may cost significantly more in total interest than a shorter-term loan, even where monthly payments are lower.
Additional borrowing also increases the amount secured against the property and may extend mortgage repayments later into retirement.
Important Disclaimer
Remortgaging to release equity increases the amount secured against your home and may reduce the value of your estate over time. It can also affect eligibility for certain means-tested benefits depending on your circumstances.
Before increasing borrowing, it is important to understand the long-term repayment costs, fees and potential risks involved. Speaking with an FCA-regulated mortgage broker and, where appropriate, a qualified financial adviser can help you assess whether releasing equity is the right option for your situation.
Your home may be repossessed if you do not keep up repayments on your mortgage.
- Totally impartial — we work for you, not the lender
- Whole-of-market access to thousands of deals
- Flexible appointments — evenings & weekends available
- We handle all the paperwork & lender negotiations
- FCA regulated — your advice is always protected
perfect mortgage?
Get in touch for a free, no-obligation consultation with one of our expert advisers. We’ll do all the hard work for you.
Get in TouchSpeak with a Sussex Remortgage Specialist
If you are thinking about remortgaging to release equity, book your free 15-minute call with Everest Mortgages. As a Brighton and Sussex-focused whole-of-market mortgage broker, we help homeowners compare remortgage options, assess affordability and understand the long-term impact of increasing borrowing secured against their home.
FAQs
1. Can I release equity from my home through remortgaging?
Yes, some homeowners may be able to release equity by remortgaging to a larger mortgage amount than their current balance. The amount available depends on factors such as property value, existing mortgage balance, income, affordability, credit profile and lender criteria.
2. How much equity do I need to remortgage?
This depends on the lender and the type of remortgage. Many lenders require homeowners to retain a percentage of equity in the property after borrowing. Loan-to-value (LTV) limits often affect how much can be released, alongside affordability and credit checks.
3. Can I remortgage for home improvements?
Yes, remortgaging to release equity for home improvements may be possible depending on your circumstances. Sussex homeowners commonly use additional borrowing for extensions, loft conversions, kitchen renovations, energy-efficiency upgrades and structural repairs.
4. Can I remortgage to consolidate debt?
Some homeowners use remortgaging to consolidate unsecured debts such as credit cards, loans or car finance into one monthly mortgage payment. While this can reduce monthly outgoings, it may increase the total amount repaid over the full mortgage term.
Consolidating unsecured debt into your mortgage may reduce monthly payments, but it can increase the total amount repaid over the full mortgage term.
5. What alternatives are there to releasing equity through remortgaging?
Depending on your circumstances, alternatives may include downsizing, using savings, unsecured borrowing, retirement interest-only mortgages, lifetime mortgages or specialist later-life lending products. The right option depends on affordability, long-term plans, costs and lender criteria.